Eldorado Gold Corporation (TSX: ELD) (NYSE: EGO) today reports the Company’s financial and operational results for the third quarter of 2026. For further information, please see the Company’s Consolidated Financial Statements and Management’s Discussion and Analysis filed on SEDAR+ at www.sedarplus.com under the Company’s profile.
Third Quarter 2026 Highlights
Operations
Financial
(1) These financial measures or ratios are non-IFRS financial measures or ratios. Certain additional disclosure for non-IFRS financial measures and ratios have been incorporated by reference and additional detail can be found at the end of this news release and in the section ‘Non-IFRS and Other Financial Measures and Ratios’ in the Company’s September 30, 2026 MD&A.
(2) The Skouries Term Facility is defined as the Commercial Loan Facility, the RRF Facility and the Contingent Overrun Facility.
Production and Cost Outlook
Production Guidance
Based on year-to-date performance through the third quarter, Eldorado has revised its 2026 production outlook for its operating assets, excluding Skouries and McIlvenna Bay, to 410,000 to 430,000 ounces of gold, compared with original guidance of 430,000 to 490,000 ounces. The revised 2026 production outlook, including Skouries and McIlvenna Bay, is 425,000 to 475,000 ounces of gold, compared with original guidance of 495,000 to 600,000 ounces. Strong performance at Lamaque, supported by increasing contributions from high-grade Ormaque ore, is partially offsetting lower expected production at Kisladag and Olympias as well as the impact of a slower than expected ramp-up at Skouries.
Base metal production ranges, including Skouries and McIlvenna Bay, have also been revised primarily reflecting the slower-than-expected ramp-up at Skouries, and lower production at Olympias:
Cost Guidance
Consolidated total cash cost guidance for operating assets, excluding Skouries and McIlvenna Bay, has been revised to $1,400 to $1,500 per ounce sold, compared with original guidance of $1,220 to $1,420 per ounce sold. AISC guidance has been revised to $1,975 to $2,125 per ounce sold, compared to original guidance of $1,670 to $1,870 per ounce sold. The revisions primarily reflect:
Capital Guidance
Skouries – With commercial production expected in late Q4, total project capital for Skouries is estimated at approximately $1.425 billion, an increase that consists of $65 million of projects costs and $45 million of previously guided growth capital that had been expected following commercial production but is now expected to be incurred prior to commercial production and is therefore reported as project capital. The increase primarily reflects higher contractor requirements to complete construction and commissioning activities, the extended use of temporary generator sets prior to connection to permanent grid power, additional owner’s costs and other project execution-related costs associated with the longer commissioning period.
Accelerated operational capital is expected to total $390 million, an increase that consists of $95 million of additional operational costs and $35 million of previously guided sustaining capital that had been expected following commercial production. It is now expected to be incurred and capitalized during the pre-commercial production period and is therefore reported as accelerated operating capital. This increase is separate from the increase in project capital.
Up to an additional $30 million may be incurred, depending on the exact timing of commercial production. The classification of these expenditures will depend on when commercial production is achieved, with amounts potentially reflected in project capital, AOC, sustaining capital or growth capital.
McIlvenna Bay – The total project capital cost estimate from June 1, 2024 to commercial production is expected to be $975 million, an increase of approximately $23 million following a slower than expected ramp-up toward commercial production. For 2026, growth capital post commercial production is expected to be approximately $15 million and sustaining capital post commercial production is expected to be $10 million.
Depreciation Expense Guidance
Depreciation expense guidance, for operating assets excluding Skouries and McIlvenna Bay, has been reduced to $225 to $235 million, compared to prior guidance of $240 to $260 million, largely due to lower production. Depreciation expense at Skouries is not expected to be significant, compared with prior guidance of $15 to $35 million, as commercial production is expected in late Q4 2026.
Corporate
Commentary
“The third quarter marked an important step forward for Eldorado. Skouries produced first copper-gold concentrate and McIlvenna Bay continued to ramp up following first copper and zinc concentrate. At Skouries, the ramp-up has taken longer and cost more than we expected, and it is important that we acknowledge that directly,” said Christian Milau, President and Chief Executive Officer. “Our focus is on safely completing the remaining commissioning work, achieving commercial production and establishing stable, predictable operating performance.
“As I begin my tenure as CEO, my focus is on building on Eldorado’s high-quality, long-life asset base and the investments already made, while improving execution consistency, enhancing capital discipline and converting those investments into stronger cash flow and per-share value. Shareholders should expect us to set clear expectations, report transparently on our progress and remain disciplined in how we allocate capital.
“Beyond the near-term ramp-ups, we have substantial opportunity within the portfolio. Our focus is on maximizing the value of the assets we already own, maintaining balance-sheet strength and financial flexibility, and investing where expected returns justify the capital. As the new operations ramp up and generate increasing cash flow, we expect to have greater flexibility to balance debt reduction, reinvestment and shareholder returns. With Skouries and McIlvenna Bay advancing through commissioning and ramp-up, our priority is to execute the remaining work and translate the cash flow potential of these investments into stronger, sustainable cash generation and per-share value.”
Skouries Highlights
The Skouries mine, part of the Kassandra Mines Complex, is located within the Halkidiki Peninsula of Northern Greece and is a high-grade copper-gold mine. In January 2022, Eldorado published the results of the Skouries Project Feasibility Study with a 20-year mine life and expected average annual production over the life of the mine of 140,000 ounces of gold and 67 million pounds of copper, or approximately 240,000 gold equivalent ounces(3).
First production of the copper-gold concentrate was achieved on September 8, 2026, and commercial production is expected late in Q4 2026. Expected 2026 gold production was revised to between 10,000 and 35,000 ounces and copper production projected to be between 5 and 15 million pounds.
(3) Gold equivalent ounces: Calculated by converting copper pounds produced into gold equivalent using budgeted commodity prices for the relevant period: 2026-2028: $4,000/oz gold and $5.00/lb copper; 2029 and beyond: $3,000/oz gold and $4.50/lb copper.
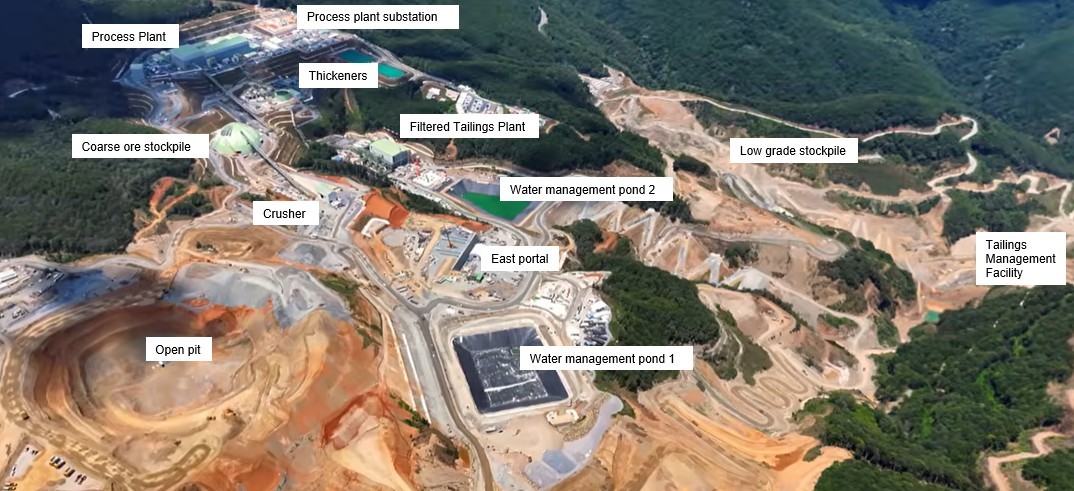
Skouries site layout
Concentrate Off-Take Agreements
The Company has secured concentrate agreements with multiple offtakers for all anticipated Skouries production volumes for the next two years, with additional counterparty agreements in process covering production through to 2029. Market conditions for copper-gold concentrate remain highly competitive.
Capital Estimate and Schedule
With commercial production expected in late Q4, total project capital for Skouries is estimated at approximately $1.425 billion, an increase that consists of $65 million of projects costs and $45 million of previously guided growth capital that had been expected following commercial production but is now expected to be incurred prior to commercial production and is therefore reported as project capital. The increase primarily reflects higher contractor requirements to complete construction and commissioning activities, the extended use of temporary generator sets prior to connection to permanent grid power, additional owner’s costs and other project execution-related costs associated with the longer commissioning period.
Accelerated operational capital is expected to total $390 million, an increase that consists of $95 million of additional operational costs and $35 million of previously guided sustaining capital that had been expected following commercial production. It is now expected to be incurred and capitalized during the pre-commercial production period and is therefore reported as accelerated operating capital. This increase is separate from the increase in project capital.
Up to an additional $30 million may be incurred, depending on the exact timing of commercial production. The classification of these expenditures will depend on when commercial production is achieved, with amounts potentially reflected in project capital, AOC, sustaining capital or growth capital.
Based on the Company’s current schedule and cost assumptions, the project remains fully funded through available cash, operating cash flow and existing debt facilities.
The Term Facility totalling €740.4 million ($840.7 million) is fully drawn (including the Contingent Overrun Facility of €60.0 million which was drawn in Q2 2026).(4)
Project capital totalled $108.6 million in Q3 2026 and $398.9 million during the nine months ended September 30, 2026. Accelerated operational capital cost totalled $84.3 million in Q3 2026, and $192.5 million during the nine months ended September 30, 2026. At September 30, 2026, cumulative project capital invested towards Phase 2 of construction totalled $1.379 billion, and the cumulative accelerated operational capital totalled $285.6 million.
(4) See the section “Financial Condition and Liquidity – Financing Activities” in the Company’s September 30, 2026 MD&A.
Operating Activities
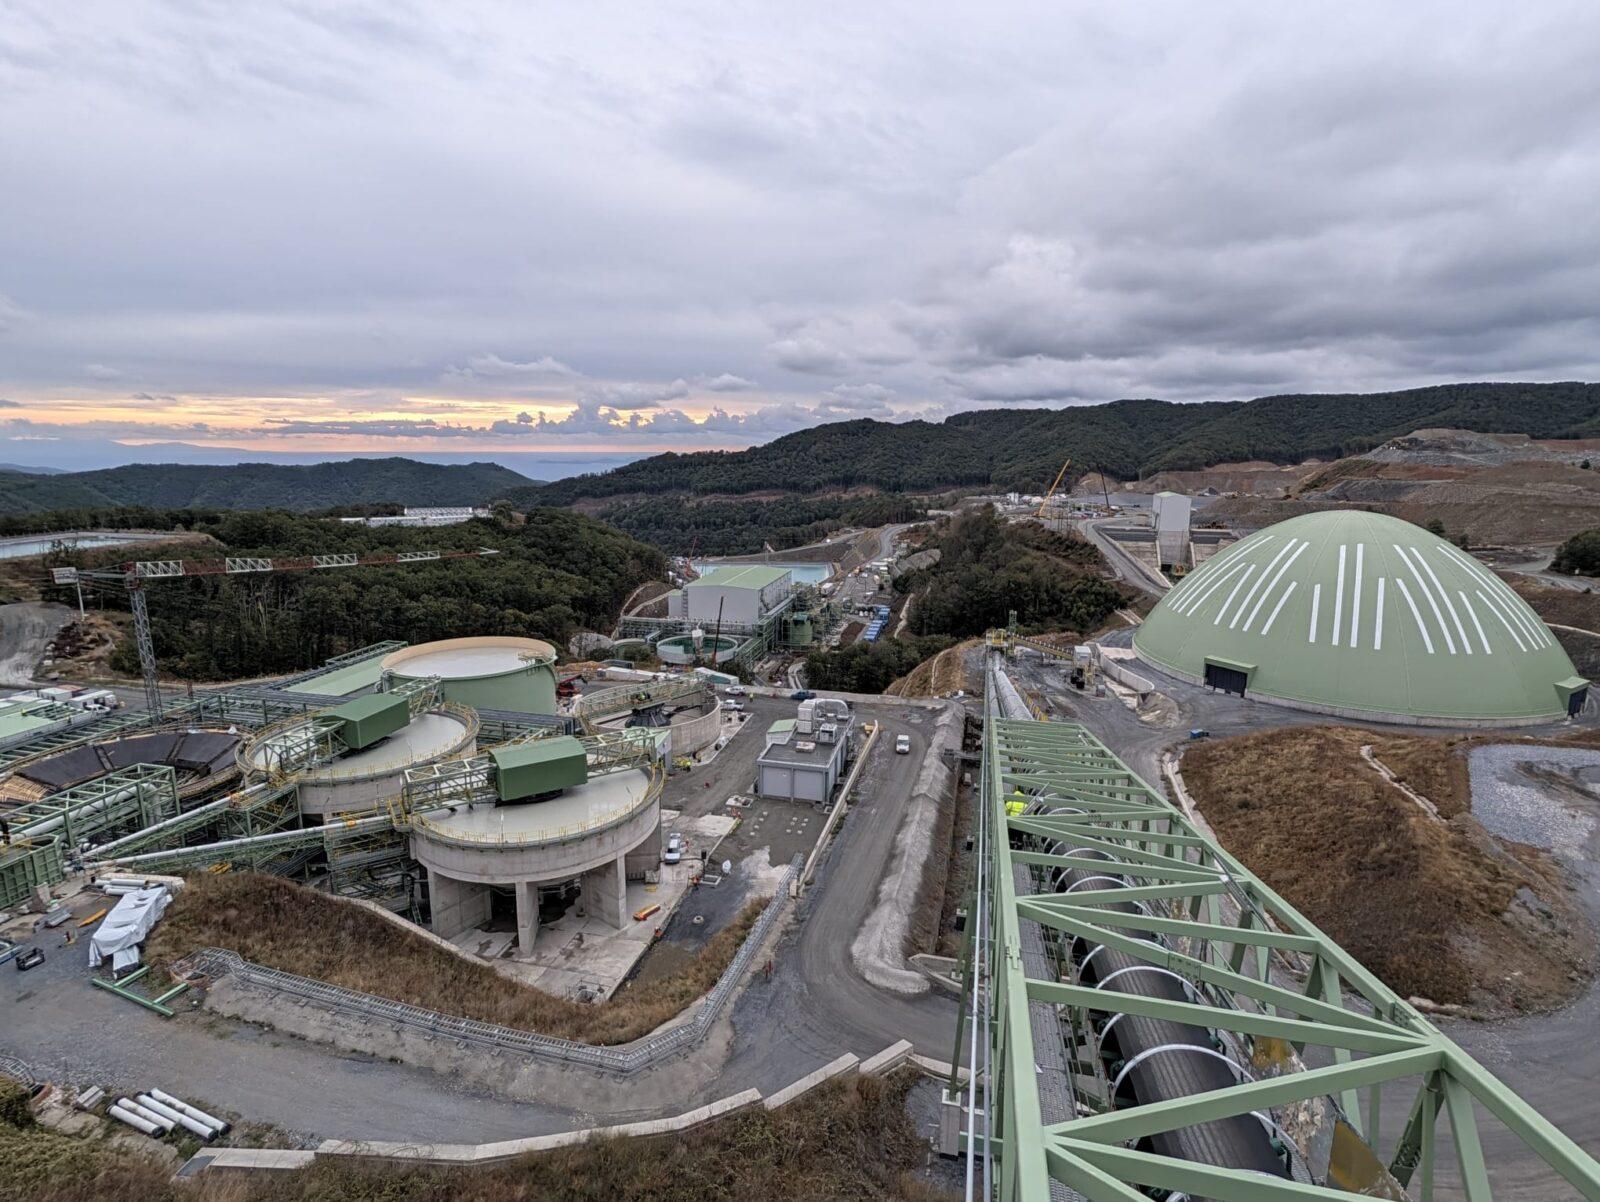
View of coarse ore stockpile dome (right), thickeners (left), filtered tailings building (background)
Primary Crusher Building
The primary crusher crushed first ore in July and is now operating as part of the integrated processing circuit. The stockpile dome, ancillary feeders and associated chute work are complete and supporting ongoing operations.
Process Plant
The process plant is substantially complete, and operating as part of the ongoing ramp-up of the operation. Commissioning activities have advanced across the processing circuit, with ore being processed through to concentrate production. Optimization and performance testing of various systems continue as part of the ramp-up to commercial production.
Thickeners
Two of the three tailings thickeners have been commissioned and are supporting current operations. Construction of the third tailings thickener, which is not required to achieve commercial production, is progressing, with completion expected in Q4 2026.
Filtered Tailings Facility
Commissioning of the filtered tailings facility continues to progress with two of the six filter presses operational. With these filter presses online, the plant is operating continuously and progressively increasing throughput as commissioning advances and the remaining filter presses are brought online. Commissioning of the remaining four filter presses is expected to be completed in November 2026.
Associated tailings handling infrastructure continues to be commissioned to support long-term operations.
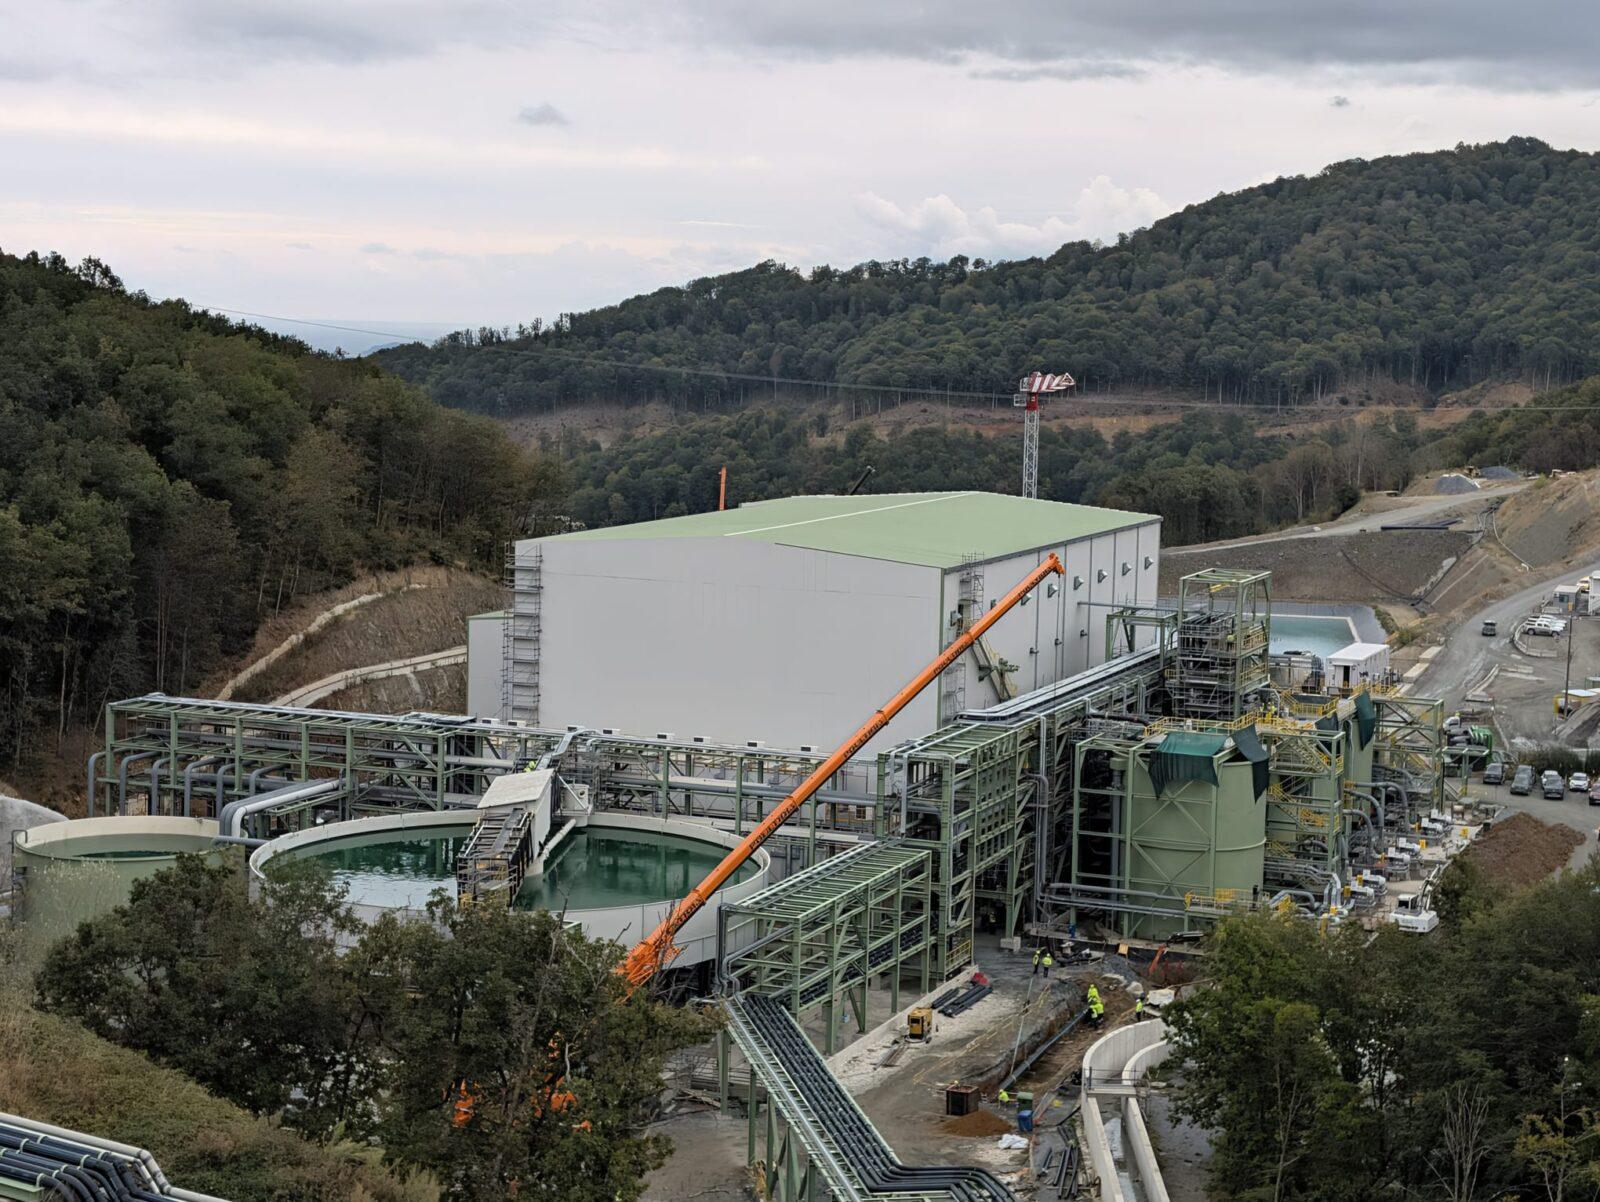
Filtered Tailings Facility
Powerline and Substations
The site was successfully energized on September 28, 2026, marking the completion of its connection to permanent grid power. The connection supports the ongoing commissioning and ramp-up of key systems across the site and provides the reliable, long-term power infrastructure required for the operations. All the temporary generators have been demobilized and removed from site.
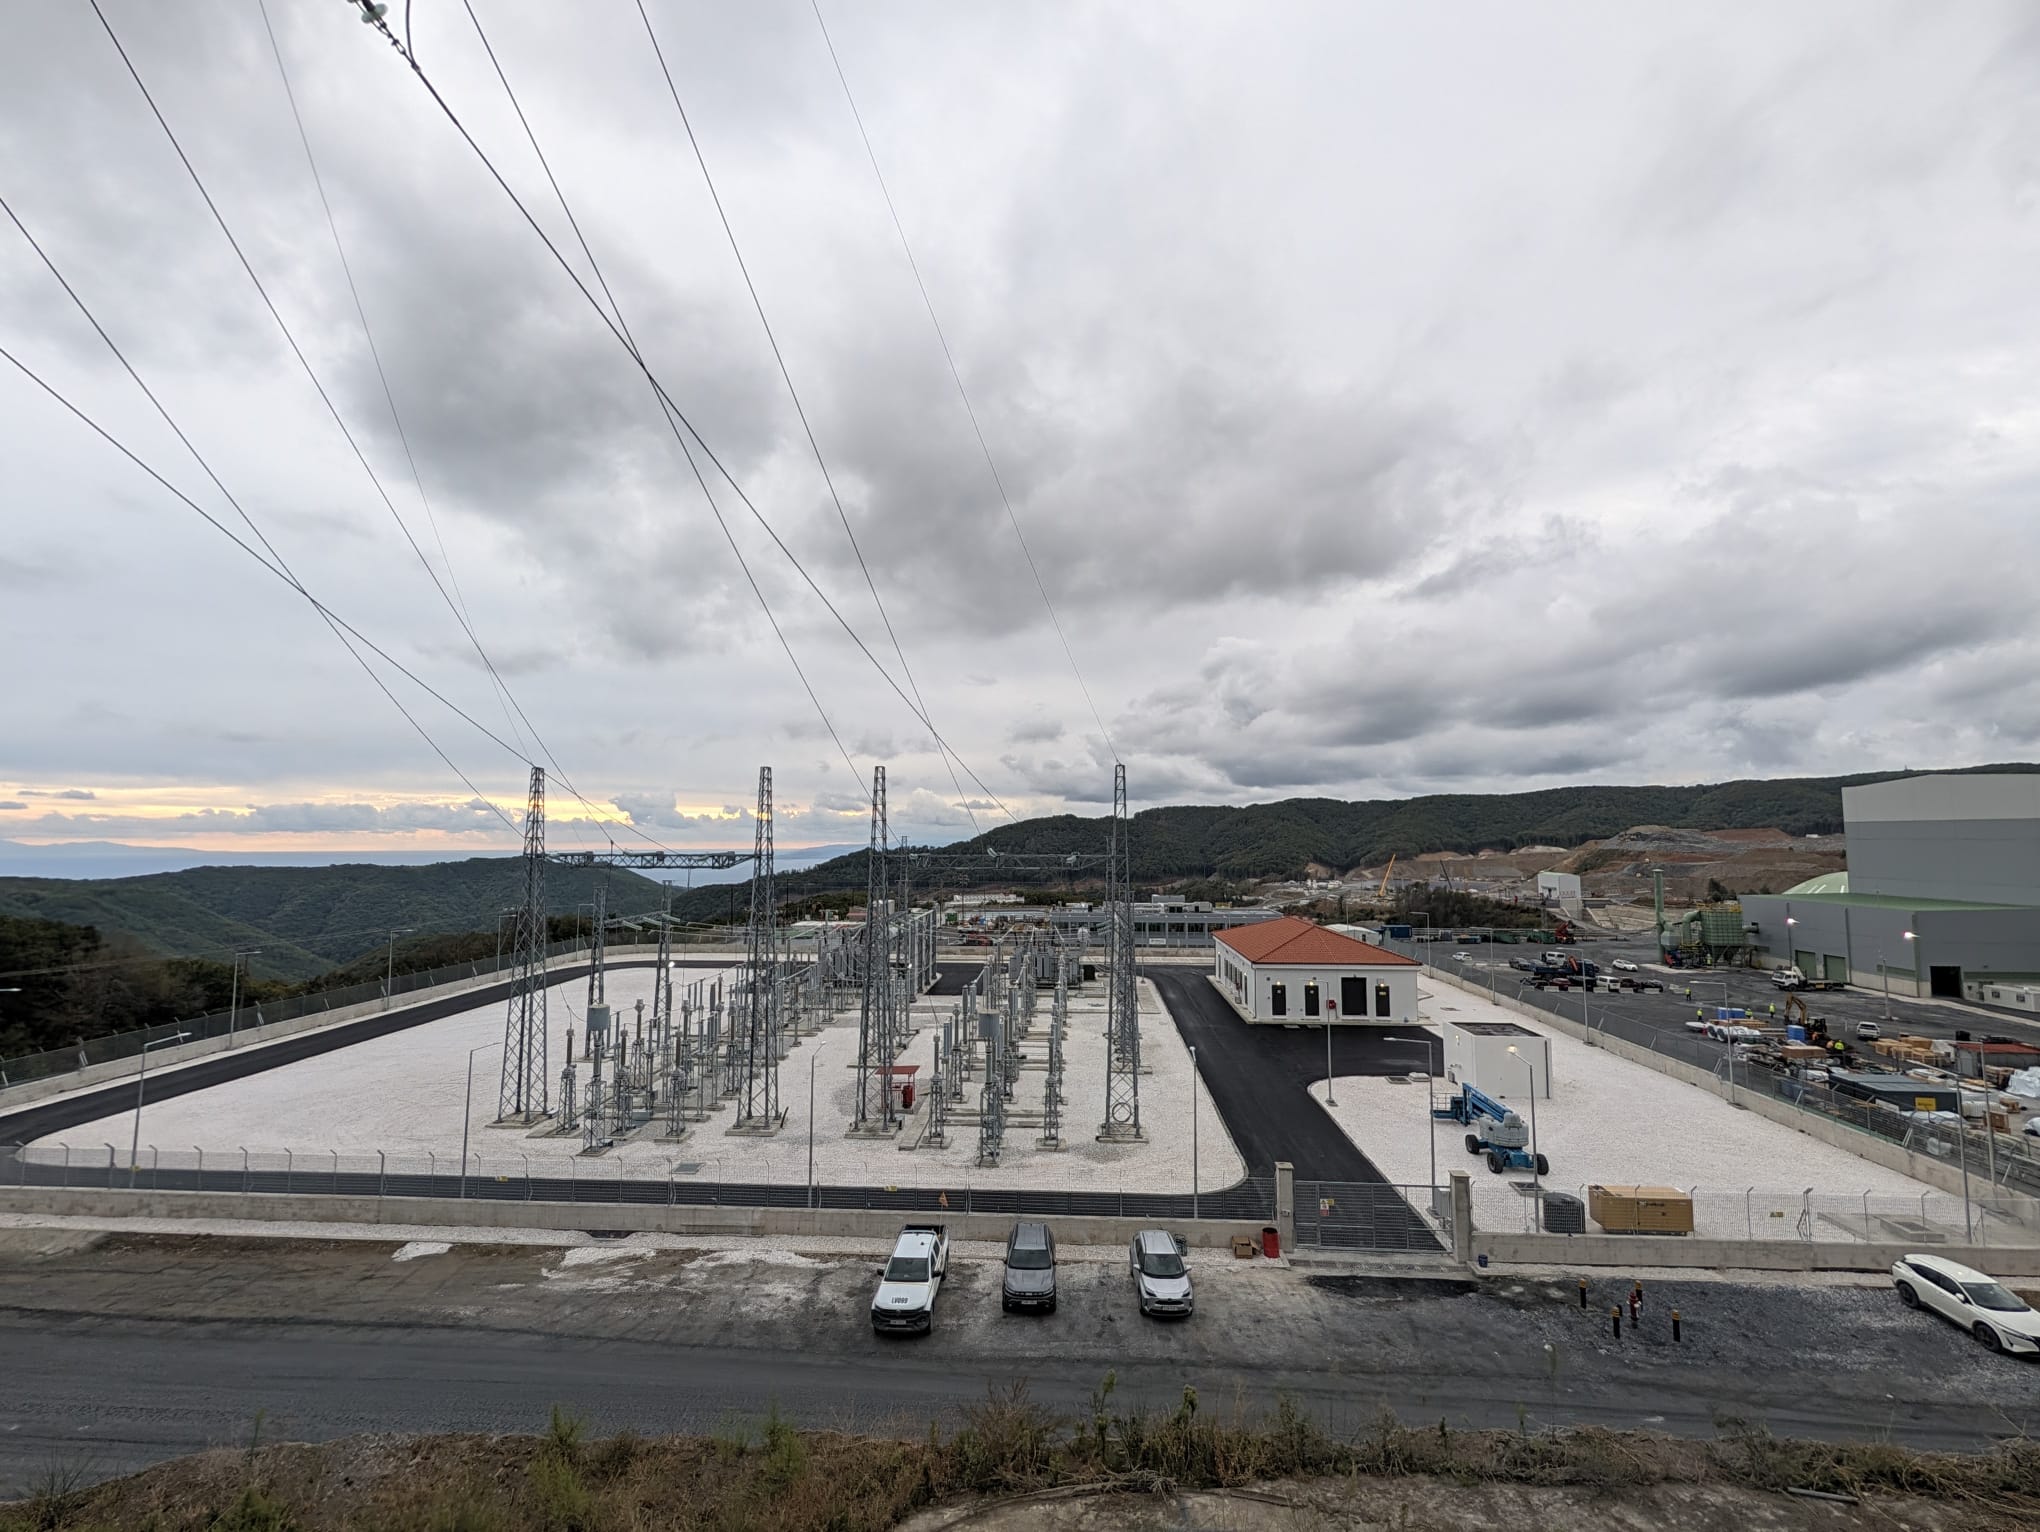
Process plant substation
Integrated Extractive Waste Management Facility
The initial filtered tailings placement areas are well advanced. The platform for the tailings stacker is complete and ready for assembly, while the access ramp and platform for the mobile (grasshopper) conveyors have been excavated and prepared for placement of the conveyor units. Construction of the rock buttress supporting the downstream embankment of the first filtered tailings placement area in the Karatza Lakkos valley is progressing and will be completed ahead of tailings placement.
Foundation preparation for the first phase of the KL filtered tailings embankment is substantially complete, and placement of engineered fill is underway across the full footprint.
Construction of the low-grade ore stockpile continued advancing. The lower section has been completed and construction is now focusing on the upper section.
Open Pit Mining
The open pit mine is feeding the crusher from both the stockpile and directly from the open pit. At the end of Q3 2026, the stockpiles contained approximately 4.8 million tonnes of open pit and underground ore, representing an estimated 176,000 ounces of gold and 61 million pounds of copper.
Underground Development
The underground mine delivered 179 kt of ore to stockpiles during Q3 2026. Underground development continued according to plan, with a total of 2,101 metres of development during the quarter. The east ramp breakthrough to the underground works was achieved during the quarter and both ramps are now providing access in and out of the underground.
Workforce
As at September 30, 2026, there were approximately 2,297 personnel working on site, including 622 Skouries employees.
McIlvenna Bay Highlights
The McIlvenna Bay mine, located in Saskatchewan, Canada, is a copper-zinc-gold-silver mine that Eldorado acquired through its acquisition of Foran, which closed on April 14, 2026. In March 2025, Foran published a McIlvenna Bay Project Feasibility Study, with an 18-year mine life and expected average annual production over the life of the mine of 41 million pounds of copper, 20,000 ounces of gold, 444,000 ounces of silver and 54 million pounds of zinc.
First production of copper concentrate from McIlvenna Bay was achieved in June 2026 with production of first zinc concentrate achieved in July. The focus is now on optimizing operations and increasing throughput to full design capacity. The crushing, grinding and flotation circuits have been commissioned and are demonstrating increasing throughput as ramp-up progresses. Remaining ramp-up activities are focused primarily on solid-liquid separation in the pyrite and tailings thickeners, reagent control, and improving filtration rates and filter availability. Work in these areas continues to advance, with commercial production expected in late Q4 2026.
The mine is expected to have a long life and is supported by a robust resource base, with highly prospective exploration upside across the broader district, including the nearby Tesla Zone. The inaugural Inferred Mineral Resource for Tesla is expected to be included in our annual Mineral Reserve and Mineral Resource update in the fourth quarter of 2026. Based on the prospectivity of the resource, we have initiated studies to evaluate material handling options for the mine, in addition to the mill expansion study that is underway, with resource conversion drilling planned for the Tesla resource. Once studies and conversion drilling have been advanced, we would expect to update the McIlvenna Bay Technical Report.
Located in one of the world’s most attractive mining jurisdictions, the mine benefits from established infrastructure and is designated by the Government of Canada as a project of national significance to support critical mineral development.
| 3 months ended Sept 30, | 9 months ended Sept 30, | |
| Operating Data | 2026 | 2026 |
| Tonnes milled | 58,832 | 64,237 |
| Head grade (% copper) | 1.06% | 1.06% |
| Head grade (% zinc) | 0.83% | 0.76% |
| Head grade (g/t gold) | 0.34 | 0.33 |
| Head grade (g/t silver) | 14.57 | 14.02 |
| Copper produced (lb) | 1,023,794 | 1,089,192 |
| Copper sold (lb) | 1,022,964 | 1,022,964 |
| Zinc produced (t) | 35 | 35 |
| Zinc sold (t) | 16 | 16 |
| Gold produced (oz) | 387 | 411 |
| Gold sold (oz) | 380 | 380 |
| Silver produced (oz) | 17,857 | 18,603 |
| Silver sold (oz) | 18,715 | 18,715 |
2026 Production and Cost Guidance; Project Capital Estimate
Production at McIlvenna Bay in 2026 is expected to be 5 to 10 million pounds of copper, 3,000 to 6,000 tonnes of zinc, 5,000 to 10,000 ounces of gold and 100,000 to 200,000 ounces of silver. Operating costs are expected to trend toward the previously disclosed range of between $90 and $110 per tonne as throughput increases and the operation progresses toward stable production levels.
The total project capital cost estimate from June 1, 2024 to commercial production is expected to be $975 million, an increase of approximately $23 million following a slower than expected ramp-up toward commercial production. For 2026, growth capital post commercial production is expected to be approximately $15 million and sustaining capital post commercial production is expected to be $10 million.
Project capital totalled $87.5 million during Q3 2026 (and $165.7 million reported from the date of acquisition of April 14, 2026). During the fourth quarter the remaining spend relates to the final commissioning and ramp-up activities required to support commercial production.
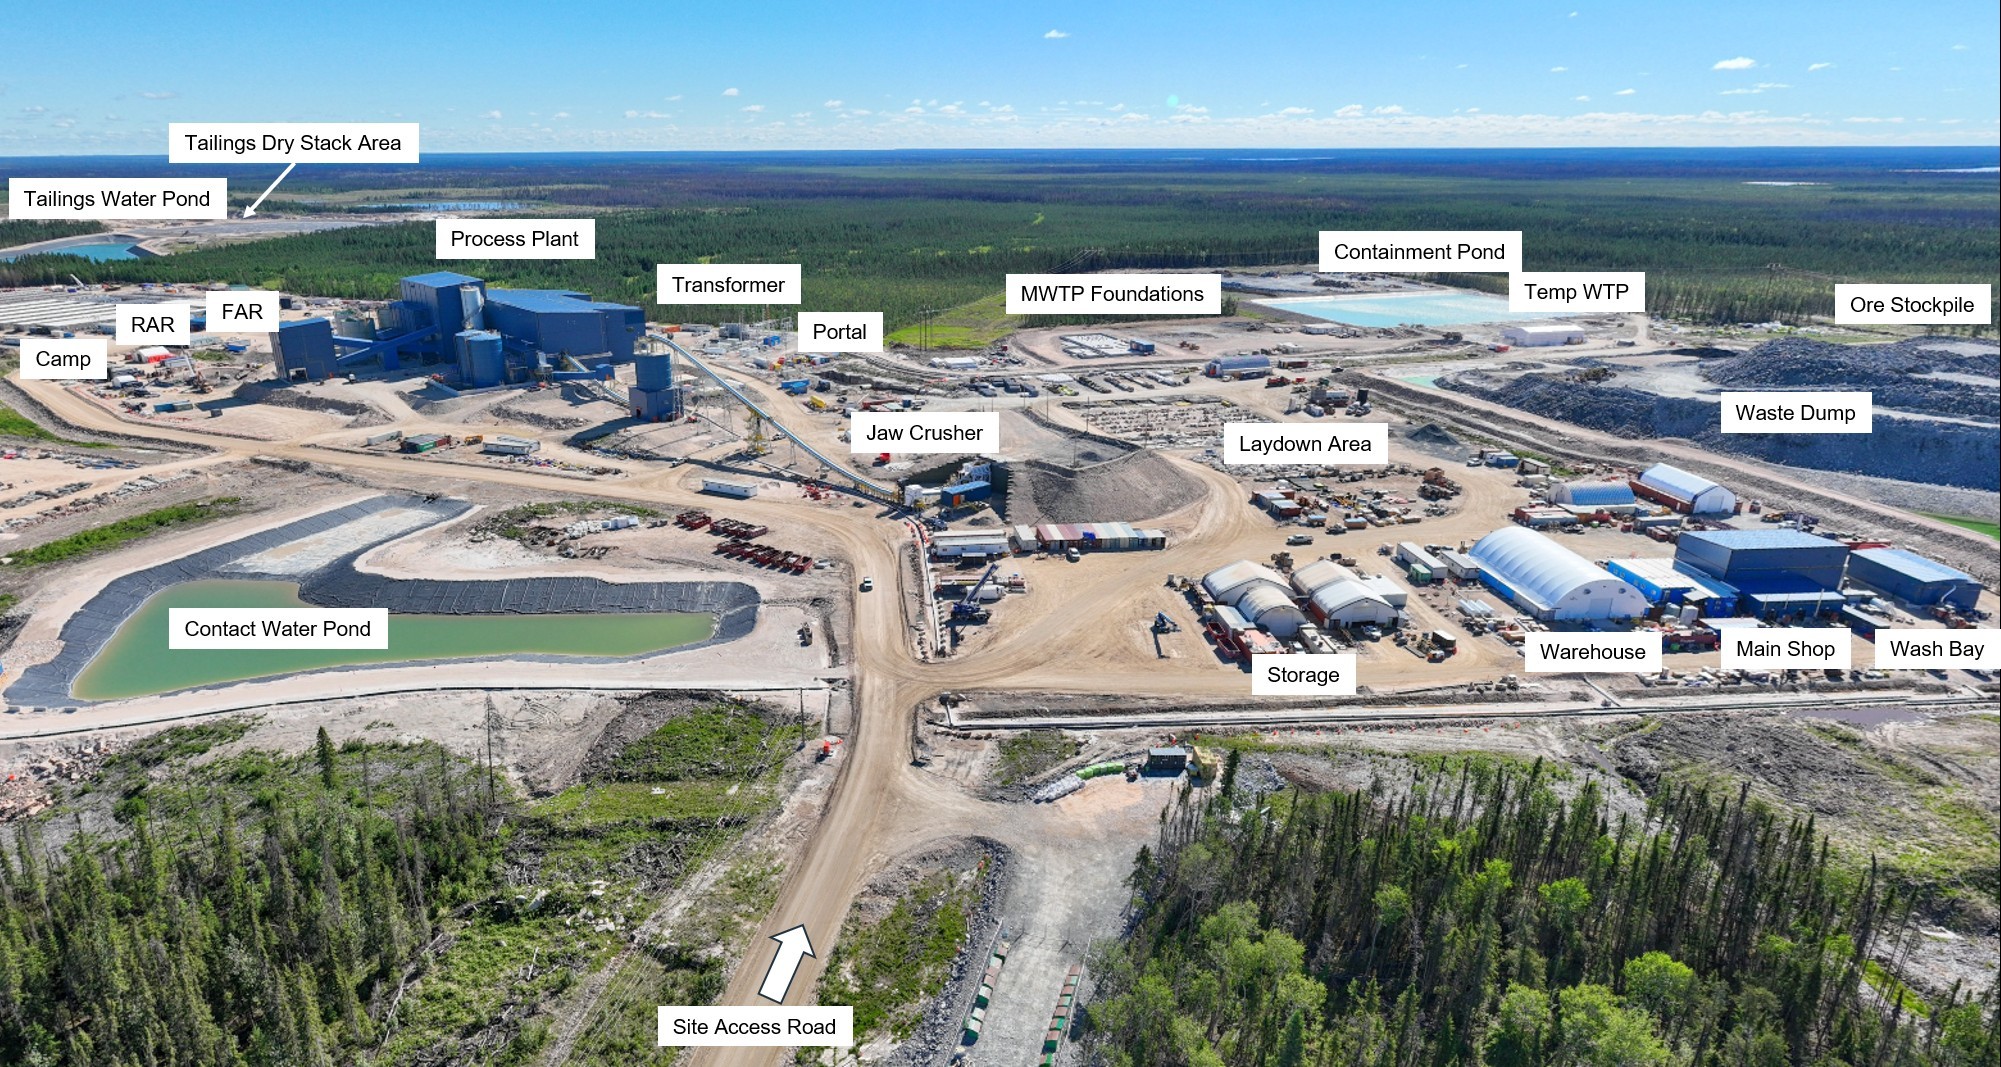
McIlvenna Bay Mine Site Overview
Operating Activities
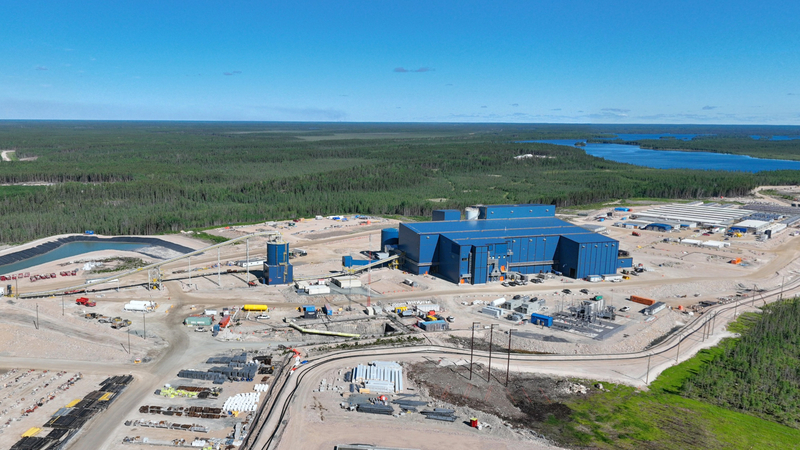
McIlvenna Bay Aerial
Primary Crusher Building
More than 400 kt of ore is available on surface for processing. The primary crusher is operating at design capacity, material transfer to the fine ore bin is as expected, and metal separation practices for underground material continue on surface.
Process Plant
The SAG and ball mill circuits continue to demonstrate increasing throughput as commissioning advances. As expected for a new processing plant, we continue to work through equipment, instrumentation and other availability-related challenges associated with ramp-up. Throughput is expected to continue increasing through the fourth quarter as the operation progresses toward commercial production.
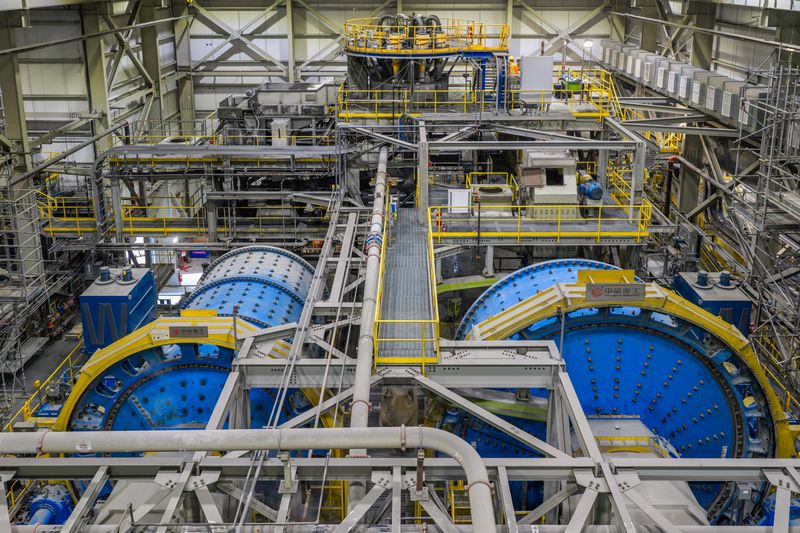
SAG and Ball Mills
Flotation
All flotation circuits are fully commissioned and have successfully produced copper, zinc and pyrite concentrates. The regrind circuit is operational and supporting further improvements in concentrate quality as ramp-up progresses.
Thickening & Filtration
The thickening and filtration circuits are key to the ramp-up of production. The key operational focus is on reagent addition and thickener control which has impacted the solid-liquid separation quality and downstream process water clarity. The teams are working to optimize the thickener and filtration processes for long-term stability.
Underground Development
Underground development continues to advance well. In addition to the 409 kt of ore stockpiled on surface, the mine has approximately 63 kt of blasted inventory, more than 400 kt drilled off, and approximately 2.0 Mt of fully developed reserves within Block 1 and Block 2.
Study Commenced on Processing Expansion, Including Throughput Increase and Silver-Lead Circuit
The expansion study is underway to evaluate an increase in processing throughput and the incorporation of a silver‑lead circuit. The expansion will evaluate a potential increase of processing capacity at McIlvenna Bay from 4,900 tonnes per day to approximately 7,000 tonnes per day. The addition of a dedicated silver‑lead circuit into the flowsheet is expected to enable recovery of lead into a separate concentrate and improve payable silver recoveries relative to the current design.
This initial study will assess the technical, economic, environmental and permitting considerations associated with the expansion. Any future development would be subject to completion of the project evaluation, receipt of required permits, Indigenous and Stakeholder engagement, and a positive final investment decision. The Company is targeting commissioning of the silver‑lead circuit in 2028 and the expansion in 2030.
Positioned as the Foundation for Long-Term District Growth
The McIlvenna Bay mine is core to our view of the district-scale geological potential to deliver future satellite development opportunities. Ongoing exploration will target additional resources, which could support further expansion or a separate processing facility over time. The 2026 exploration program includes approximately 14,000 metres of diamond drilling focused on resource expansion, high-grade extensions, and advancing regional targets.
In parallel, core scanning programs will enhance geological modelling and orebody characterization. Airborne and ground geophysical surveys are expected to help refine known deposit footprints and identify new targets across the broader land package.
Consolidated Financial and Operational Highlights
41
1
| 3 months ended September 30, | 9 months ended September 30, | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||||||||||||||||||
| Revenue | $ | 511.9 | $ | 434.7 | $ | 1,531.7 | $ | 1,241.7 | ||||||||||||||||||||||||||||||||||||||||||
| Gold produced (oz) | 106,351 | 115,190 | 311,325 | 364,852 | ||||||||||||||||||||||||||||||||||||||||||||||
| Gold sold (oz) | 107,164 | 116,529 | 310,474 | 364,281 | ||||||||||||||||||||||||||||||||||||||||||||||
| Average realized gold price ($/oz sold)(2) | $ | 4,326 | $ | 3,527 | $ | 4,527 | $ | 3,245 | ||||||||||||||||||||||||||||||||||||||||||
| Production costs | 199.8 | 164.1 | 572.8 | 474.6 | ||||||||||||||||||||||||||||||||||||||||||||||
| Total cash costs ($/oz sold)(2,3) | 1,415 | 1,195 | 1,438 | 1,134 | ||||||||||||||||||||||||||||||||||||||||||||||
| All-in sustaining costs ($/oz sold)(2,3) | 2,050 | 1,679 | 1,974 | 1,583 | ||||||||||||||||||||||||||||||||||||||||||||||
| Net earnings for the period(1) | 118.0 | 56.0 | 427.2 | 266.4 | ||||||||||||||||||||||||||||||||||||||||||||||
| Net earnings per share – basic ($/share)(1) | 0.45 | 0.28 | 1.80 | 1.31 | ||||||||||||||||||||||||||||||||||||||||||||||
| Net earnings per share – diluted ($/share)(1) | 0.45 | 0.27 | 1.78 | 1.29 | ||||||||||||||||||||||||||||||||||||||||||||||
| Net earnings for the period continuing operations(1,4) | 118.0 | 56.5 | 427.2 | 267.5 | ||||||||||||||||||||||||||||||||||||||||||||||
| Net earnings per share continuing operations – basic ($/share)(1,4) | 0.45 | 0.28 | 1.80 | 1.31 | ||||||||||||||||||||||||||||||||||||||||||||||
| Net earnings per share continuing operations – diluted ($/share)(1,4) | 0.45 | 0.28 | 1.78 | 1.30 | ||||||||||||||||||||||||||||||||||||||||||||||
| Adjusted net earnings(1,2,4) | 127.0 | 82.3 | 451.9 | 228.8 | ||||||||||||||||||||||||||||||||||||||||||||||
| Adjusted net earnings per share – basic ($/share)(1,2,4) | 0.49 | 0. | .91 | 1.12 | ||||||||||||||||||||||||||||||||||||||||||||||
| Net cash generated from operating activities(4) | 134.8 | 170.2 | 425.7 | 458.8 | ||||||||||||||||||||||||||||||||||||||||||||||
| Cash flow from operating activities before changes in working capital(2,4) | 248.8 | 183.5 | 539.0 | 522.0 | ||||||||||||||||||||||||||||||||||||||||||||||
| Free cash flow(2,4) | (191.1 | ) | (87.4 | ) | (654.3 | ) | (178.4 | ) | ||||||||||||||||||||||||||||||||||||||||||
| Free cash flow excluding Skouries and McIlvenna Bay(2,4,5) | 98.3 | 76.9 | 202.1 | 206.3 | ||||||||||||||||||||||||||||||||||||||||||||||
| Cash and cash equivalents(4) | 396.8 | 1,043.9 | 396.8 | 1,043.9 | ||||||||||||||||||||||||||||||||||||||||||||||
| Restricted cash – current(6) | 71.9 | — | 71.9 | — | ||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | 10,616.9 | 6,485.4 | 10,616.9 | 6,485.4 | ||||||||||||||||||||||||||||||||||||||||||||||
| Debt | 1,985.4 | 1,258.5 | 1,985.4 | 1,258.5 | ||||||||||||||||||||||||||||||||||||||||||||||
(1) Attributable to shareholders of the Company.
(2) These financial measures or ratios are non-IFRS financial measures or ratios. See the section ‘Non-IFRS and Other Financial Measures and Ratios’ of our MD&A for explanations and discussions of these non-IFRS financial measures or ratios.
(3) Includes costs allocated to by-products.
(4) 2025 amounts presented are from continuing operations only and exclude the Romania segment which was carried as a discontinued operation and disposed in Q4 2025.
(5) Amounts presented add back cash-basis capital expenditure on the Skouries mine in the respective periods and the McIlvenna Bay mine only in 2026.
(6) In accordance with the requirements of the Skouries Term Facility the Company deposited an amount of €63.3 million ($71.9 million) which is equal to at least 50% of the aggregate repayment installments, fees, interest, financing costs and charges of the Term Facility for the next 12 months, into a Debt Service Reserve Account.
In Q3 2026, we produced 106,351 ounces of gold, a decrease from Q3 2025 production of 115,190 ounces. The decrease was driven by decreases at Kisladag, due to the planned lower ore grade stacked, and at Efemcukuru, due to lower ore grade, partially offset by higher production at Lamaque as a result of higher throughput, grade and recoveries, which includes the positive impact of Ormaque ore grades and improving productivity.
Gold sales in Q3 2026 were 107,164 ounces, a decrease from 116,529 ounces sold in Q3 2025. The lower sales volume reflects lower production at Kisladag and Efemcukuru, partially offset by higher production at Lamaque.
The average realized gold price was $4,326 per ounce sold in Q3 2026, an increase from $3,527 per ounce sold in Q3 2025.
Total revenue increased to $511.9 million in Q3 2026 from $434.7 million in Q3 2025 and to $1,531.7 million in the nine months ended September 30, 2026, from $1,241.7 million in the nine months ended September 30, 2025. The increases in both periods were due to the higher average realized gold price, partially offset by lower volumes sold.
Production costs increased to $199.8 million in Q3 2026 from $164.1 million in Q3 2025 and to $572.8 million in the nine months ended September 30, 2026 from $474.6 million in the nine months ended September 30, 2025. Increases in both periods were driven by higher royalties and the inclusion of pre-commercial production costs at McIlvenna Bay, together which accounted for approximately 32% and 45% of the increase to production costs for Q3 2026 and the nine months ended September 30, 2026, respectively. The remainder relates primarily to increases at Lamaque, due to increased volumes produced, higher maintenance costs and deepening the production centre of the Triangle Mine, and at Olympias due to higher labour, contractor and materials costs as well as higher volumes sold.
Production costs include royalty expense, which increased to $31.8 million in Q3 2026 from $28.8 million in Q3 2025 and increased to $115.7 million in the nine months ended September 30, 2026 from $79.6 million in the nine months ended September 30, 2025. Increases in both periods were due to higher average realized gold prices and higher royalty rates, partially offset by lower volumes sold.
Total cash costs(5) averaged $1,415 per ounce sold in Q3 2026, an increase from $1,195 in Q3 2025, and $1,438 in the nine months ended September 30, 2026 from $1,134 in the nine months ended September 30, 2025. The increases in both the three and nine-month periods were primarily due to higher production costs and lower volumes sold, partially offset by higher costs allocated to by-products.
AISC per ounce sold(5) averaged $2,050 in Q3 2026, an increase from $1,679 in Q3 2025, and $1,974 in the nine months ended September 30, 2026 from $1,583 in the nine months ended September 30, 2025. The increases in both periods were driven by higher total cash costs, higher sustaining capital expenditures and lower volumes sold.
The Company reported net earnings attributable to shareholders from continuing operations of $118.0 million ($0.45 earnings per share) in Q3 2026 compared to net earnings of $56.5 million ($0.28 earnings per share) in Q3 2025 and net earnings of $427.2 million ($1.80 earnings per share) in the nine months ended September 30, 2026 compared to net earnings of $267.5 million ($1.31 earnings per share) in the nine months ended September 30, 2025. The increase in net earnings in both periods were driven by higher average realized gold prices, foreign exchange gains and lower depreciation, partially offset by lower volumes sold, higher production costs and higher income tax expense.
Adjusted net earnings(5) was $127.0 million ($0.49 adjusted earnings per share) in Q3 2026 compared to adjusted net earnings of $82.3 million ($0.41 adjusted earnings per share) in Q3 2025. Adjustments of non-recurring items in Q3 2026 include a $7.4 million loss on foreign exchange translation of deferred tax balances and a $4.0 million unrealized gain on derivative instruments.
Adjusted net earnings(5) was $451.9 million ($1.91 adjusted earnings per share) in the nine months ended September 30, 2026 compared to adjusted net earnings of $228.8 million ($1.12 adjusted earnings per share) in the nine months ended September 30, 2025. Adjustments of non-recurring items in the nine months ended September 30, 2026 include a reversal of $100.6 million of unrealized losses on derivative instruments, a $97.6 million realized loss on gold and copper commodity swaps relating to the Term Facility, a $41.5 million loss on foreign exchange due to the translation of deferred tax balances, a $47.4 million gain on deferred tax due to changes in the Turkish corporate income tax rate, and a $21.3 million expense relating to acquisition and integration costs.
(5) These financial measures or ratios are non-IFRS financial measures or ratios. Certain additional disclosure for non-IFRS financial measures and ratios have been incorporated by reference and additional detail can be found at the end of this news release and in the section ‘Non-IFRS and Other Financial Measures and Ratios’ in the Company’s September 30, 2026 MD&A.
Quarterly Operations Update
| 3 months ended September 30, | 9 months ended September 30, | |||||||
| 2026 | 2025 | 2026 | 2025 | |||||
| Consolidated | ||||||||
| Gold produced (oz)(3) | 106,351 | 115,190 | 311,325 | 364,852 | ||||
| Gold sold (oz)(4) | 107,164 | 116,529 | 310,474 | 364,281 | ||||
| Production costs(5) | $199.8 | $164.1 | $572.8 | $474.6 | ||||
| Total cash costs ($/oz sold)(1,2) | $1,415 | $1,195 | $1,438 | $1,134 | ||||
| All-in sustaining costs ($/oz sold)(1,2) | $2,050 | $1,679 | $1,974 | $1,583 | ||||
| Sustaining capital expenditures(2) | $52.1 | $38.3 | $120.0 | $115.2 | ||||
| Kisladag | ||||||||
| Gold produced (oz) | 22,713 | 37,184 | 70,160 | 127,561 | ||||
| Gold sold (oz) | 21,274 | 37,300 | 68,974 | 126,928 | ||||
| Production costs | $51.1 | $50.1 | $149.4 | $150.3 | ||||
| Total cash costs ($/oz sold)(1,2) | $2,328 | $1,309 | $2,072 | $1,152 | ||||
| All-in sustaining costs ($/oz sold)(1,2) | $2,832 | $1,545 | $2,396 | $1,324 | ||||
| Sustaining capital expenditures(2) | $9.2 | $7.3 | $18.3 | $16.0 | ||||
| Lamaque | ||||||||
| Gold produced (oz) | 52,748 | 46,823 | 147,394 | 137,901 | ||||
| Gold sold (oz) | 55,475 | 46,013 | 150,142 | 137,665 | ||||
| Production costs | $50.5 | $36.0 | $136.5 | $107.9 | ||||
| Total cash costs ($/oz sold)(1,2) | $897 | $767 | $889 | $772 | ||||
| All-in sustaining costs ($/oz sold)(1,2) | $1,436 | $1,199 | $1,335 | $1,270 | ||||
| Sustaining capital expenditures(2) | $29.4 | $19.2 | $65.7 | $67.3 | ||||
| Efemcukuru | ||||||||
| Gold produced (oz) | 17,073 | 17,586 | 50,486 | 57,986 | ||||
| Gold sold (oz) | 15,908 | 20,031 | 49,426 | 58,600 | ||||
| Production costs | $33.8 | $32.3 | $110.1 | $85.5 | ||||
| Total cash costs ($/oz sold)(1,2) | $1,928 | $1,522 | $2,013 | $1,405 | ||||
| All-in sustaining costs ($/oz sold)(1,2) | $2,313 | $1,791 | $2,356 | $1,674 | ||||
| Sustaining capital expenditures(2) | $5.8 | $4.9 | $16.1 | $14.3 | ||||
| Olympias | ||||||||
| Gold produced (oz) | 13,430 | 13,597 | 42,874 | 41,404 | ||||
| Gold sold (oz) | 14,127 | 13,185 | 41,552 | 41,088 | ||||
| Production costs | $56.0 | $45.8 | $168.4 | $130.9 | ||||
| Total cash costs ($/oz sold)(1,2) | $1,493 | $1,869 | $1,688 | $1,910 | ||||
| All-in sustaining costs ($/oz sold)(1,2) | $2,067 | $2,421 | $2,199 | $2,367 | ||||
| Sustaining capital expenditures(2) | $7.6 | $6.9 | $19.9 | $17.6 | ||||
(1) Includes costs allocated to by-products.
(2) These financial measures or ratios are non-IFRS financial measures or ratios. See the section ‘Non-IFRS and Other Financial Measures and Ratios’ of our MD&A for explanations and discussions of these non-IFRS financial measures or ratios.
(3) Includes 387 and 411 pre-commercial gold ounces produced at McIlvenna Bay for the three and nine months ended September 30, 2026 respectively.
(4) Includes 380 pre-commercial gold ounces sold at McIlvenna Bay for the three and nine months ended September 30, 2026.
(5) Includes $8.4 million of pre-commercial production costs for McIlvenna Bay for the three and nine months ended September 30, 2026.
Kisladag
Kisladag produced 22,713 ounces of gold in Q3 2026 compared to 37,184 ounces in Q3 2025, with the decrease due to lower planned grades associated with the current cutback and slower-than-planned mining progress, which delayed access to higher-grade material during the third quarter. Ore grade decreased to 0.55 grams per tonne in Q3 2026 from 0.70 grams per tonne in Q3 2025, partially offset by higher stacked tonnage, resulting in lower recoverable ounces during the quarter.
Revenue decreased to $93.1 million in Q3 2026 from $130.5 million in Q3 2025, reflecting a decrease in gold ounces sold that was partially offset by the higher average realized gold price.
Production costs increased to $51.1 million in Q3 2026 from $50.1 million in Q3 2025, driven by higher labour and contractor costs, higher maintenance and higher reagent costs for water management, offset by lower gold sales and lower royalty costs. Lower gold production and higher production costs were primarily responsible for the increase in total cash costs per ounce sold to $2,328 in Q3 2026 from $1,309 in Q3 2025.
AISC per ounce sold increased to $2,832 in Q3 2026 from $1,545 in Q3 2025, primarily due to higher cash costs per ounce sold and higher sustaining costs.
Sustaining capital expenditures were $9.2 million in Q3 2026 and $18.3 million in the nine months ended September 30, 2026, which primarily included a new 300 tonne haul truck purchase, planned equipment rebuilds (including primary crusher refurbishment), interlifts for the leach pad and geotechnical drilling. Growth capital investment of $38.9 million and $122.7 million in the three and nine months ended September 30, 2026 was primarily due to waste stripping and associated equipment costs, continued construction of the North Heap Leach Pad Phase 3, construction of the whole-ore agglomeration circuit and upgrades to the secondary crusher. Growth capital in the nine months ended September 30, 2026, also included one-time land purchases totalling $23.9 million required for the construction of the NHLP and North Rock Dump.
Kisladag incurred higher reagent costs as a result of increased water management activities, predominantly in the second quarter following a period of higher‑than‑average precipitation in the first half of 2026, that resulted in elevated water levels within site ponds. The Company continues to actively manage water balances across the operation, with a focus on continuing to maximize on‑site water capture and reuse in support of its sustainability objectives, and has constructed additional water storage capacity to enhance operational flexibility.
The Company continues to evaluate a pit shell based on gold price sensitivity analysis, which is expected to support further expansion into the western area of the pit and support resource expansion. New geological and metallurgical information will be incorporated into the life-of-mine optimization that will form part of the Mineral Reserve and Mineral Resource update expected in Q4 2026. As part of this optimization work, the Company expects to evaluate an investment decision on additional screening before year-end.
Progress on construction of the whole ore agglomeration circuit, which is configured to increase permeability and reduce leach time, is on track with earthworks well underway and all long-lead items procured. Commissioning and ramp-up are expected in H1 2027.
Overall, this mine optimization plan is expected to support improved sequencing of ore and waste movement, and with implementation of whole ore agglomeration, is expected to contribute to more consistent year‑over‑year operating performance and higher production over the longer term.
Lamaque
Lamaque produced 52,748 ounces of gold in Q3 2026, an increase of 13% from 46,823 ounces in Q3 2025. The increase was due to higher throughput, head grade and recoveries, benefiting from strong mill performance and ore from Ormaque following receipt of the operating authorization in March.
Revenue increased to $239.7 million in Q3 2026 from $160.7 million in Q3 2025, driven by the combination of higher gold ounces sold and higher average realized price.
Production costs increased to $50.5 million in Q3 2026 from $36.0 million in Q3 2025, reflecting higher costs and higher volume sold. As the centre of production at the Triangle Mine deepens, additional costs are incurred for haulage, equipment (including maintenance) and personnel requirements. Total cash costs per ounce sold increased to $897 in Q3 2026 from $767 in Q3 2025 due to higher production costs, including mining costs for Ormaque, and higher royalties, partially offset by higher number of ounces sold.
AISC per ounce sold was $1,436 in Q3 2026 compared to $1,199 in Q3 2025, primarily due to higher sustaining capital driven by the inclusion of the non-ramp capitalized development at Ormaque commencing from July 2026, but also impacted by higher total cash costs partially offset by higher ounces sold.
Sustaining capital expenditures of $29.4 million in Q3 2026 and $65.7 million in the nine months ended September 30, 2026 primarily included underground development (including Ormaque non-ramp underground development from July onwards), equipment rebuilds, delineation drilling and purchases. Growth capital investment of $41.5 million in Q3 2026 and $107.5 million in the nine months ended September 30, 2026 was primarily related to Ormaque development (up to the end of June, following which Ormaque non-ramp development is being reported as sustaining capital), construction of the paste plant, construction of the north basin water management structure, and continued ramp development at both the Triangle Mine and Ormaque.
Efemcukuru
Efemcukuru produced 17,073 ounces of gold in Q3 2026 compared to 17,586 ounces in Q3 2025. The decrease was primarily due to planned lower ore grade, which decreased to 4.44 grams per tonne in Q3 2026 from 4.71 grams per tonne in Q3 2025, partially offset by higher mill throughput and recovery.
Revenue decreased to $72.8 million in Q3 2026 from $77.8 million in Q3 2025. The decrease was driven by lower gold ounces sold impacted by a concentrate shipment delayed to October, partially offset by higher average realized gold prices.
Production costs increased to $33.8 million in Q3 2026 from $32.3 million in Q3 2025, primarily due to higher royalty expense as a result of higher gold prices, as well as increased labour and maintenance costs. On a per ounce sold basis, higher royalties and direct operating costs combined with lower gold sold resulted in an increase to total cash costs per ounce sold to $1,928 in Q3 2026 from $1,522 in Q3 2025.
AISC per ounce sold increased to $2,313 in Q3 2026 from $1,791 in Q3 2025, primarily due to lower gold ounces sold, slightly higher total cash costs and slightly higher sustaining capital expenditures.
Sustaining capital expenditures of $5.8 million in Q3 2026 and $16.1 million in the nine months ended September 30, 2026 were primarily underground development and equipment rebuilds. Growth capital investment of $9.4 million in Q3 2026 and $17.6 million in the nine months ended September 30, 2026 related to development costs at Bati, portal development at Kokarpinar, construction of a water pond and mine rock storage facility, and equipment purchases.
Olympias
Olympias produced 13,430 ounces of gold in Q3 2026 compared to 13,597 ounces in Q3 2025, driven by lower gold grades, partially offset by higher mill throughput combined with a stable ore blend and flotation performance which resulted in increased metal recoveries. Grades were lower than planned as a result of material with elevated lead and zinc content that had been expected to be processed during the third quarter and was stockpiled and is expected to be blended through a controlled blending program during the fourth quarter to maintain process stability and optimize recoveries.
Revenue increased to $96.7 million in Q3 2026 from $65.8 million in Q3 2025, due to the higher average realized gold price, higher by-product sales on higher production, and higher gold ounces sold.
Production costs increased to $56.0 million in Q3 2026 from $45.8 million in Q3 2025 driven by higher labour costs and royalties as a result of higher gold prices combined with higher metal volumes sold. On a per ounce sold basis, higher by-product credits and modestly higher ounces sold, partially offset by higher direct operating costs and higher royalties, decreased total cash costs per ounce sold to $1,493 in Q3 2026 from $1,869 in Q3 2025.
AISC per ounce sold decreased to $2,067 in Q3 2026 from $2,421 in Q3 2025 primarily due to lower total cash costs and slightly higher gold ounces sold.
Sustaining capital expenditures of $7.6 million in Q3 2026 and $19.9 million in the nine months ended September 30, 2026 primarily included underground development, underground resource classification drilling, upgraded underground electrical and ventilation control, filter press refurbishment, and mobile mining equipment rebuilds and purchases. Growth capital investment of $15.3 million in Q3 2026 and $37.7 million in the nine months ended September 30, 2026 was primarily related to the mill expansion project and to a lesser extent, underground development and equipment purchases.
At Olympias, production has stabilized over the past four quarters, with flotation recoveries returning to modelled levels. Completion of the 650 ktpa expansion, including the new greenfield infrastructure (commissioning of the tower mill, gold thickener, zinc filter and flotation circuit extension), is ongoing. The final circuit tie-ins will require a full plant shutdown which is expected in Q1 2027, with ramp‑up to nameplate capacity anticipated in H1 2027.
For further information on the Company’s operating results for the third quarter of 2026, please see the Company’s MD&A filed on SEDAR+ at www.sedarplus.com under the Company’s profile.
Conference Call
A conference call to discuss the details of the Company’s Third Quarter 2026 Results will be held by senior management on Thursday, October 29, 2026 at 9:00 AM ET (6:00 AM PT). The call will be webcast and can be accessed at Eldorado’s website: www.eldoradogold.com or via this link:
https://event.choruscall.com/mediaframe/webcast.html?webcastid=XFFI5roL
Participants may elect to pre-register for the conference call via this link: https://dpregister.com/sreg/10211449/104b751968a
Upon registration, participants will receive a calendar invitation by email with dial in details and a unique PIN. This will allow participants to bypass the operator queue and connect directly to the conference. Registration will remain open until the end of the conference call.
| Conference Call Details | Replay (available until December 10, 2026) | |||
| Date: | October 29, 2026 | Vancouver: | +1 412 317 0088 | |
| Time: | 9:00 AM ET (6:00 AM PT) | Toll Free: | +1 855 669 9658 | |
| Dial in: | +1 647 846 2782 | Access code: | 4538447 | |
| Toll free: | +1 833 752 3325 | |||
About Eldorado
Eldorado is a gold, copper and base metals producer with mining, development and exploration operations in Canada, Greece and Turkiye. The Company has a highly skilled and dedicated workforce, safe and responsible operations, a portfolio of high-quality assets, and long-term partnerships with local communities. Eldorado’s common shares trade on the Toronto Stock Exchange (TSX: ELD) and the New York Stock Exchange (NYSE: EGO).
Contact
Investor Relations
Lynette Gould, VP, Investor Relations, Communications & External Affairs
647 271 2827 or 1 888 353 8166
lynette.gould@eldoradogold.com
Media
Chad Pederson, Director, Communications and Public Affairs
236 885 6251 or 1 888 353 8166
chad.pederson@eldoradogold.com
Qualified Persons and Disclosure of Mineral Resources
Except as otherwise noted, Simon Hille, FAusIMM, Executive Vice President and Chief Operating Officer, is the Qualified Person under NI 43-101 responsible for preparing and supervising the preparation of the scientific and technical information contained in this news release and verifying the technical data disclosed in this document relating to our operating mines and development projects.
Jessy Thelland, géo (OGQ No. 758), a member in good standing of the Ordre des Géologues du Québec, is the qualified person as defined in NI 43-101 responsible for, and has verified and approved, the scientific and technical disclosure contained in this news release for the Quebec projects.
Mineral resources that are not mineral reserves do not have demonstrated economic viability. Inferred mineral resources are considered too speculative geologically to have the economic considerations applied to them that would enable them to be categorized as mineral reserves.
Eldorado Gold Corporation
Condensed Consolidated Interim Statements of Financial Position
As at September 30, 2026 and December 31, 2025
(Unaudited – in thousands of U.S. dollars)
| Note | September 30, 2026 | December 31, 2025 | |||||||
| ASSETS | |||||||||
| Current assets | |||||||||
| Cash and cash equivalents | $ | 396,828 | $ | 869,356 | |||||
| Restricted cash | 8 | 71,898 | — | ||||||
| Accounts receivable and other | 5 | 219,086 | 279,212 | ||||||
| Inventories | 6 | 475,726 | 297,165 | ||||||
| Current derivative assets | 17 | 845 | 2,051 | ||||||
| 1,164,383 | 1,447,784 | ||||||||
| Deferred tax assets | 45,421 | 37,076 | |||||||
| Other assets | 7 | 86,112 | 144,479 | ||||||
| Investment in associate | 123,275 | 109,423 | |||||||
| Non-current derivative assets | 17 | 7,848 | 10,380 | ||||||
| Property, plant and equipment | 8,651,071 | 4,885,564 | |||||||
| Goodwill | 4 | 538,772 | 92,591 | ||||||
| $ | 10,616,882 | $ | 6,727,297 | ||||||
| LIABILITIES & EQUITY | |||||||||
| Current liabilities | |||||||||
| Accounts payable and accrued liabilities | $ | 658,294 | $ | 630,310 | |||||
| Current portion of lease liabilities | 5,547 | 6,024 | |||||||
| Current portion of debt | 8 | 148,472 | 47,968 | ||||||
| Current portion of asset retirement obligation | 5,866 | 7,886 | |||||||
| Current derivative liabilities | 17 | 4,441 | 96,879 | ||||||
| 822,620 | 789,067 | ||||||||
| Debt | 8 | 1,836,954 | 1,227,084 | ||||||
| Lease liabilities | 8,656 | 8,575 | |||||||
| Employee benefit plan obligation | 14,514 | 13,747 | |||||||
| Asset retirement obligation | 139,709 | 135,071 | |||||||
| Non-current derivative liabilities | 17 | 4,068 | 16,254 | ||||||
| Deferred income tax liabilities | 823,664 | 254,420 | |||||||
| 3,650,185 | 2,444,218 | ||||||||
| Equity | |||||||||
| Share capital | 13 | 5,701,273 | 3,341,760 | ||||||
| Shares held in trust for restricted share units | 13 | (18,960 | ) | (16,035 | ) | ||||
| Contributed surplus | 2,492,172 | 2,537,197 | |||||||
| Accumulated other comprehensive loss | (31,156 | ) | (11,553 | ) | |||||
| Deficit | (1,179,293 | ) | (1,572,080 | ) | |||||
| Total equity attributable to shareholders of the Company | 6,964,036 | 4,279,289 | |||||||
| Attributable to non-controlling interests | 2,661 | 3,790 | |||||||
| 6,966,697 | 4,283,079 | ||||||||
| $ | 10,616,882 | $ | 6,727,297 | ||||||
Commitments and contractual obligations (Note 16)
Events after the reporting date (Note 13(b))
Approved on behalf of the Board of Directors
(signed) Teresa Conway Director (signed) Christian Milau Director
Date of approval: October 28, 2026
Eldorado Gold Corporation
Condensed Consolidated Interim Statements of Operations
For the three and nine months ended September 30, 2026 and 2025
(Unaudited – in thousands of U.S. dollars except share and per share amounts)
| Three months ended | Nine months ended | ||||||||||||||||
| September 30, | September 30, | ||||||||||||||||
| Note | 2026 | 2025 | 2026 | 2025 | |||||||||||||
| Revenue | |||||||||||||||||
| Metal sales | 9 | $ | 511,860 | $ | 434,727 | $ | 1,531,744 | $ | 1,241,696 | ||||||||
| Cost of sales | |||||||||||||||||
| Production costs | 199,821 | 164,140 | 572,822 | 474,609 | |||||||||||||
| Depreciation and amortization | 58,722 | 62,829 | 166,959 | 188,961 | |||||||||||||
| 258,543 | 226,969 | 739,781 | 663,570 | ||||||||||||||
| Earnings from mine operations | 253,317 | 207,758 | 791,963 | 578,126 | |||||||||||||
| Exploration and evaluation expenses | 17,116 | 10,975 | 41,408 | 25,218 | |||||||||||||
| Mine standby costs | 6,318 | 6,465 | 17,082 | 15,252 | |||||||||||||
| General and administrative expenses | 11,177 | 9,503 | 34,462 | 28,191 | |||||||||||||
| Share-based payments expense | 14 | 3,763 | 6,802 | 10,197 | 15,347 | ||||||||||||
| Write-down of assets | 1,569 | 3,261 | 2,672 | 8,426 | |||||||||||||
| Foreign exchange (gain) loss | (4,029 | ) | 32 | (38,262 | ) | 24,840 | |||||||||||
| Acquisition costs | 4 | 89 | — | 19,253 | — | ||||||||||||
| Earnings from operations | 217,314 | 170,720 | 705,151 | 460,852 | |||||||||||||
| Other income (expense) | 10 | 5,613 | (52,406 | ) | 15,821 | (115,145 | ) | ||||||||||
| Finance costs | 11 | (13,531 | ) | (8,221 | ) | (37,660 | ) | (21,134 | ) | ||||||||
| Earnings from continuing operations before income tax | 209,396 | 110,093 | 683,312 | 324,573 | |||||||||||||
| Income tax expense | 12 | 91,605 | 53,917 | 257,114 | 54,604 | ||||||||||||
| Net earnings from continuing operations | 117,791 | 56,176 | 426,198 | 269,969 | |||||||||||||
| Net loss from discontinued operations, net of tax | — | (1,122 | ) | — | (6,578 | ) | |||||||||||
| Net earnings for the period | $ | 117,791 | $ | 55,054 | $ | 426,198 | $ | 263,391 | |||||||||
| Net earnings (loss) attributable to: | |||||||||||||||||
| Shareholders of the Company | 117,954 | 56,027 | 427,150 | 266,438 | |||||||||||||
| Non-controlling interests | (163 | ) | (973 | ) | (952 | ) | (3,047 | ) | |||||||||
| Net earnings for the period | $ | 117,791 | $ | 55,054 | $ | 426,198 | $ | 263,391 | |||||||||
| Net earnings (loss) attributable to shareholders of the Company: | |||||||||||||||||
| Continuing operations | 117,954 | 56,540 | 427,150 | 267,522 | |||||||||||||
| Discontinued operations | — | (513 | ) | — | (1,084 | ) | |||||||||||
| $ | 117,954 | $ | 56,027 | $ | 427,150 | $ | 266,438 | ||||||||||
| Net (loss) earnings attributable to non-controlling interests: | |||||||||||||||||
| Continuing operations | (163 | ) | (364 | ) | (952 | ) | 2,447 | ||||||||||
| Discontinued operations | — | (609 | ) | — | (5,494 | ) | |||||||||||
| $ | (163 | ) | $ | (973 | ) | $ | (952 | ) | $ | (3,047 | ) | ||||||
| Weighted average number of shares outstanding: | |||||||||||||||||
| Basic | 13 | 260,941,591 | 202,742,582 | 236,944,753 | 204,129,778 | ||||||||||||
| Diluted | 13 | 263,448,182 | 205,150,042 | 239,640,842 | 206,247,722 | ||||||||||||
| Net earnings per share attributable to shareholders of the Company: | |||||||||||||||||
| Basic earnings per share | $ | 0.45 | $ | 0.28 | $ | 1.80 | $ | 1.31 | |||||||||
| Diluted earnings per share | $ | 0.45 | $ | 0.27 | $ | 1.78 | $ | 1.29 | |||||||||
| Net earnings per share attributable to shareholders of the Company – Continuing operations: | |||||||||||||||||
| Basic earnings per share | $ | 0.45 | $ | 0.28 | $ | 1.80 | $ | 1.31 | |||||||||
| Diluted earnings per share | $ | 0.45 | $ | 0.28 | $ | 1.78 | $ | 1.30 | |||||||||
Eldorado Gold Corporation
Condensed Consolidated Interim Statements of Comprehensive Income
For the three and nine months ended September 30, 2026 and 2025
(Unaudited – in thousands of U.S. dollars)
| Three months ended | Nine months ended | ||||||||||||||||
| September 30, | September 30, | ||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | ||||||||||||||
| Net earnings for the period | $ | 117,791 | $ | 55,054 | $ | 426,198 | $ | 263,391 | |||||||||
| Other comprehensive (loss) income: | |||||||||||||||||
| Items that will not be reclassified to earnings or loss: | |||||||||||||||||
| Change in fair value of investments in marketable securities | (135 | ) | 32,584 | 60 | 62,521 | ||||||||||||
| Income tax expense on change in fair value of investments in marketable securities | — | (4,388 | ) | (31 | ) | (8,394 | ) | ||||||||||
| Actuarial gain (loss) on employee benefit plans | 370 | (359 | ) | 142 | 61 | ||||||||||||
| Income tax expense on employee benefit plans | (89 | ) | (32 | ) | (34 | ) | (133 | ) | |||||||||
| Total other comprehensive income for the period | 146 | 27,805 | 137 | 54,055 | |||||||||||||
| Total comprehensive income for the period | $ | 117,937 | $ | 82,859 | $ | 426,335 | $ | 317,446 | |||||||||
| Total comprehensive income (loss) attributable to: | |||||||||||||||||
| Shareholders of the Company | 118,100 | 83,832 | 427,287 | 320,493 | |||||||||||||
| Non-controlling interests | (163 | ) | (973 | ) | (952 | ) | (3,047 | ) | |||||||||
| $ | 117,937 | $ | 82,859 | $ | 426,335 | $ | 317,446 | ||||||||||
Eldorado Gold Corporation
Condensed Consolidated Interim Statements of Cash Flows
For the three and nine months ended September 30, 2026 and 2025
(Unaudited – in thousands of U.S. dollars)
| Three months ended | Nine months ended | ||||||||||||||||
| September 30, | September 30, | ||||||||||||||||
| Note | 2026 | 2025 | 2026 | 2025 | |||||||||||||
| Cash flows generated from (used in): | |||||||||||||||||
| Operating activities | |||||||||||||||||
| Net earnings from continuing operations | $ | 117,791 | $ | 56,176 | $ | 426,198 | $ | 269,969 | |||||||||
| Adjustments for: | |||||||||||||||||
| Depreciation and amortization | 59,170 | 63,342 | 168,317 | 190,374 | |||||||||||||
| Finance costs | 11 | 13,531 | 8,221 | 37,660 | 21,134 | ||||||||||||
| Interest income | 10 | (2,505 | ) | (8,561 | ) | (15,598 | ) | (25,782 | ) | ||||||||
| Share of loss from associate | 525 | — | 880 | — | |||||||||||||
| Unrealized foreign exchange (gain) loss | (4,413 | ) | (694 | ) | (32,661 | ) | 23,991 | ||||||||||
| Income tax expense | 12 | 91,605 | 53,917 | 257,114 | 54,604 | ||||||||||||
| (Gain) loss on disposal of assets | (1,453 | ) | 441 | (842 | ) | (6,618 | ) | ||||||||||
| Unrealized (gain) loss on derivative contracts | 10 | (4,028 | ) | 22,194 | (100,627 | ) | 66,844 | ||||||||||
| Write-down of assets | 1,569 | 3,261 | 2,672 | 8,426 | |||||||||||||
| Share-based payments expense | 14 | 3,763 | 6,802 | 10,197 | 15,347 | ||||||||||||
| Employee benefit plan expense | 1,424 | 719 | 3,742 | 2,820 | |||||||||||||
| 276,979 | 205,818 | 757,052 | 621,109 | ||||||||||||||
| Property reclamation payments | (1,683 | ) | (1,284 | ) | (4,078 | ) | (3,688 | ) | |||||||||
| Employee benefit plan payments | (691 | ) | (298 | ) | (1,756 | ) | (1,087 | ) | |||||||||
| Income taxes paid | (28,310 | ) | (29,316 | ) | (227,796 | ) | (120,136 | ) | |||||||||
| Interest received | 2,505 | 8,561 | 15,598 | 25,782 | |||||||||||||
| Changes in non-cash operating working capital | 15 | (113,988 | ) | (13,273 | ) | (113,273 | ) | (63,194 | ) | ||||||||
| Net cash generated from operating activities of continuing operations | 134,812 | 170,208 | 425,747 | 458,786 | |||||||||||||
| Net cash (used in) generated from operating activities of discontinued operations | — | (151 | ) | — | 158 | ||||||||||||
| Investing activities | |||||||||||||||||
| Additions to property, plant and equipment | (429,103 | ) | (242,517 | ) | (1,210,017 | ) | (592,207 | ) | |||||||||
| Capitalized interest paid | (14,879 | ) | (8,437 | ) | (45,943 | ) | (28,457 | ) | |||||||||
| Cash from acquisition of Foran Mining Corporation, net of cash paid | 4 | — | — | 159,110 | — | ||||||||||||
| Proceeds from the sale of property, plant and equipment | 2,158 | 244 | 4,539 | 3,224 | |||||||||||||
| Purchase of investment in associate | — | — | (14,731 | ) | — | ||||||||||||
| Value added taxes related to mineral property expenditures, net | 23,445 | (5,954 | ) | 68,161 | (7,005 | ) | |||||||||||
| Cash received from deferred consideration | — | 60,000 | — | 60,000 | |||||||||||||
| Sale (purchase) of investments in marketable securities | 287 | (13,961 | ) | 37,359 | 141,117 | ||||||||||||
| Increase in deposits and other investments | (5,707 | ) | (1,484 | ) | (13,716 | ) | (10,750 | ) | |||||||||
| Increase in restricted cash | 8 | (71,877 | ) | — | (71,877 | ) | — | ||||||||||
| Net cash used in investing activities of continuing operations | (495,676 | ) | (212,109 | ) | (1,087,115 | ) | (434,078 | ) | |||||||||
| Financing activities | |||||||||||||||||
| Issuance of common shares for cash, net of share issuance costs | 2,755 | 1,575 | 6,546 | 9,102 | |||||||||||||
| Net contributions from (distributions to) non-controlling interests | — | 53 | (177 | ) | (264 | ) | |||||||||||
| Net proceeds from Skouries Project Financing Facility | 8 | 14,630 | 98,549 | 47,237 | 288,314 | ||||||||||||
| Proceeds from Credit Facility, net of transaction costs | 8 | 222,983 | — | 322,983 | — | ||||||||||||
| Net (repayments) proceeds from other debt | 8 | (217 | ) | — | 2,469 | — | |||||||||||
| Term Facility commitment fees | — | — | (474 | ) | (1,372 | ) | |||||||||||
| Dividends paid | 13 | (19,619 | ) | — | (54,103 | ) | — | ||||||||||
| Interest paid | (13,165 | ) | (9,174 | ) | (28,611 | ) | (19,601 | ) | |||||||||
| Principal portion of lease liabilities | (1,402 | ) | (1,401 | ) | (3,931 | ) | (3,927 | ) | |||||||||
| Purchase of shares for cancellation | 13 | — | (78,793 | ) | (83,895 | ) | (123,381 | ) | |||||||||
| Purchase of shares held in trust for restricted share units | 13 | — | (3,955 | ) | (8,683 | ) | (8,181 | ) | |||||||||
| Net cash generated from financing activities of continuing operations | 205,965 | 6,854 | 199,361 | 140,690 | |||||||||||||
| Effect of exchange rates on cash and cash equivalents | (2,835 | ) | 410 | (10,521 | ) | 21,740 | |||||||||||
| Net (decrease) increase in cash and cash equivalents | (157,734 | ) | (34,788 | ) | (472,528 | ) | 187,296 | ||||||||||
| Cash and cash equivalents – beginning of period | 554,562 | 1,078,572 | 869,356 | 856,797 | |||||||||||||
| Change in cash in disposal group held for sale | — | 151 | — | (158 | ) | ||||||||||||
| Cash and cash equivalents – end of period | $ | 396,828 | $ | 1,043,935 | $ | 396,828 | $ | 1,043,935 | |||||||||
Eldorado Gold Corporation
Condensed Consolidated Interim Statements of Changes in Equity
For the three and nine months ended September 30, 2026 and 2025
(Unaudited – in thousands of U.S. dollars)
| Three months ended | Nine months ended | |||||||||||||||
| September 30, | September 30, | |||||||||||||||
| Note | 2026 | 2025 | 2026 | 2025 | ||||||||||||
| Share capital | ||||||||||||||||
| Balance beginning of period | $ | 5,695,878 | $ | 3,423,439 | $ | 3,341,760 | $ | 3,433,778 | ||||||||
| Shares issued upon exercise of share options | 2,755 | 1,502 | 6,546 | 9,913 | ||||||||||||
| Shares issued upon exercise of performance share units | 1,459 | — | 4,545 | 5,282 | ||||||||||||
| Shares issued upon acquisition of Foran Mining Corporation | 4 | — | — | 2,385,625 | — | |||||||||||
| Transfer of contributed surplus on exercise of options | 1,181 | 565 | 2,847 | 3,749 | ||||||||||||
| Shares repurchased and cancelled, net of tax | — | (42,467 | ) | (40,050 | ) | (68,872 | ) | |||||||||
| Shares repurchased and not yet cancelled | — | (3,892 | ) | — | (3,892 | ) | ||||||||||
| Share issuance costs | — | — | — | (811 | ) | |||||||||||
| Balance end of period | 13 | $ | 5,701,273 | $ | 3,379,147 | $ | 5,701,273 | $ | 3,379,147 | |||||||
| Shares held in trust for restricted share units | ||||||||||||||||
| Balance beginning of period | $ | (19,087 | ) | $ | (9,162 | ) | $ | (16,035 | ) | $ | (12,970 | ) | ||||
| Shares purchased and held in trust for restricted share units | — | (3,954 | ) | (8,683 | ) | (8,180 | ) | |||||||||
| Shares released for settlement of restricted share units | 127 | 225 | 5,758 | 8,259 | ||||||||||||
| Balance end of period | 13 | $ | (18,960 | ) | $ | (12,891 | ) | $ | (18,960 | ) | $ | (12,891 | ) | |||
| Contributed surplus | ||||||||||||||||
| Balance beginning of period | $ | 2,493,742 | $ | 2,583,047 | $ | 2,537,197 | $ | 2,612,762 | ||||||||
| Shares repurchased and cancelled | — | (33,876 | ) | (42,907 | ) | (52,950 | ) | |||||||||
| Share-based payment arrangements | 1,197 | 3,055 | 7,936 | 8,914 | ||||||||||||
| Option consideration on acquisition of Foran Mining Corporation | 4 | — | — | 3,096 | — | |||||||||||
| Shares redeemed upon exercise of restricted share units | (127 | ) | (225 | ) | (5,758 | ) | (8,259 | ) | ||||||||
| Shares redeemed upon exercise of performance share units | (1,459 | ) | — | (4,545 | ) | (5,282 | ) | |||||||||
| Transfer to share capital on exercise of options | (1,181 | ) | (565 | ) | (2,847 | ) | (3,749 | ) | ||||||||
| Balance end of period | $ | 2,492,172 | $ | 2,551,436 | $ | 2,492,172 | $ | 2,551,436 | ||||||||
| Accumulated other comprehensive (loss) income | ||||||||||||||||
| Balance beginning of period | $ | (31,302 | ) | $ | (21,070 | ) | $ | (11,553 | ) | $ | 56,183 | |||||
| Other comprehensive income for the period attributable to shareholders of the Company | 146 | 27,805 | 137 | 54,055 | ||||||||||||
| Reclassification on derecognition of investments in marketable securities | — | — | (19,740 | ) | (103,503 | ) | ||||||||||
| Balance end of period | $ | (31,156 | ) | $ | 6,735 | $ | (31,156 | ) | $ | 6,735 | ||||||
| Deficit | ||||||||||||||||
| Balance beginning of period | $ | (1,277,628 | ) | $ | (1,879,249 | ) | $ | (1,572,080 | ) | $ | (2,193,163 | ) | ||||
| Dividends paid | 13 | (19,619 | ) | — | (54,103 | ) | — | |||||||||
| Net earnings attributable to shareholders of the Company | 117,954 | 56,027 | 427,150 | 266,438 | ||||||||||||
| Reclassification on derecognition of investments in marketable securities | — | — | 19,740 | 103,503 | ||||||||||||
| Balance end of period | $ | (1,179,293 | ) | $ | (1,823,222 | ) | $ | (1,179,293 | ) | $ | (1,823,222 | ) | ||||
| Total equity attributable to shareholders of the Company | $ | 6,964,036 | $ | 4,101,205 | $ | 6,964,036 | $ | 4,101,205 | ||||||||
| Non-controlling interests | ||||||||||||||||
| Balance beginning of period | $ | 2,824 | $ | (10,534 | ) | $ | 3,790 | $ | (8,143 | ) | ||||||
| Loss attributable to non-controlling interests | (163 | ) | (973 | ) | (952 | ) | (3,047 | ) | ||||||||
| Net contributions from (distributions to) non-controlling interests | — | 53 | (177 | ) | (264 | ) | ||||||||||
| Balance end of period | $ | 2,661 | $ | (11,454 | ) | $ | 2,661 | $ | (11,454 | ) | ||||||
| Total equity | $ | 6,966,697 | $ | 4,089,751 | $ | 6,966,697 | $ | 4,089,751 | ||||||||
(1) These financial measures or ratios are non-IFRS financial measures or ratios. Certain additional disclosure for non-IFRS financial measures and ratios have been incorporated by reference and additional detail can be found at the end of this news release and in the section ‘Non-IFRS and Other Financial Measures and Ratios’ in the Company’s September 30, 2026 MD&A.
(2) The Skouries Term Facility is defined as the Commercial Loan Facility, the RRF Facility and the Contingent Overrun Facility.
(3) Gold equivalent ounces: Calculated by converting copper pounds produced into gold equivalent using budgeted commodity prices for the relevant period: 2026-2028: $4,000/oz gold and $5.00/lb copper; 2029 and beyond: $3,000/oz gold and $4.50/lb copper.
(4) See the section “Financial Condition and Liquidity – Financing Activities” in the Company’s September 30, 2026 MD&A.
(5) These financial measures or ratios are non-IFRS financial measures or ratios. Certain additional disclosure for non-IFRS financial measures and ratios have been incorporated by reference and additional detail can be found at the end of this news release and in the section ‘Non-IFRS and Other Financial Measures and Ratios’ in the Company’s September 30, 2026 MD&A.
First Quantum Minerals Ltd. (TSX: FM) today reports results for the three and nine months ended Sept... READ MORE
Alamos Gold Inc. (TSX:AGI) (NYSE:AGI) today reported its financial results for the quarter e... READ MORE
Kinross Gold Corporation (TSX: K) (NYSE: KGC) today announced its results for the third quarter ende... READ MORE
Imperial Metals Corporation (TSX:III) reports assay results from its spring 2026 diamond drilling pr... READ MORE