Bonterra Resources Inc. (TSX-V: BTR) (OTCQB: BONXF) (FSE: 9BR2) is pleased to announce robust results from the independent preliminary economic assessment on the Barry open pit and underground project in the Urban-Barry Camp in northern Quebec. The PEA has been prepared by BBA Consultants in accordance with National Instrument 43-101 – Standards of Disclosure for Mineral Projects. The PEA is based on the recent mineral resources estimate that was prepared by P&E Mining Consultants Inc. (see press release dated February 23, 2026). BBA has independently reviewed and endorsed the mine engineering and cost estimates as used in the PEA. The Project is under a definitive earn-in and joint venture agreement with Gold Fields Limited. Under the JV Agreement, Gold Fields, through its affiliate Windfall Mining Group Inc., has the right to acquire a 70% interest in the Project by spending C$30 million in work expenditures, with a minimum spending commitment of C$10 million per year over a three-year period (see press release dated November 28, 2023, for more details). The PEA and this news release have been prepared solely by Bonterra. Neither Gold Fields nor Windfall Mining has contributed, reviewed, verified, approved or endorsed this news release, the PEA, its assumptions or the development scenario described therein.
PEA Highlights (100% Project Basis)
Cesar Gonzalez, Executive Chairman and Interim CEO commented: “Bonterra’s PEA demonstrates the potential economic viability and robustness of the Project in a conceptual case based on a toll-milling operating model and on a 100% project basis. The PEA outlines a project requiring modest upfront investment that is expected to produce an average of 87,097 ounces of gold per year and generate average annual pre-tax net cash flow of more than C$131 million if commercial production is achieved under the development scenario contemplated by the PEA. At a spot gold price of US$4,100 per ounce, the PEA estimates an after-tax NPV of C$976 million and an after-tax IRR of 77%, highlighting the significant leverage of the Project to higher gold prices. The Project includes the existing mining lease, established infrastructure, and an underground ramp providing rapid access to the underground workings. Importantly, the PEA mine plan incorporates only approximately 40% of the contained gold ounces in the February 2026 MRE, highlighting significant potential for resource conversion and mine plan expansion, particularly as the Barry deposit remains open at depth, with mineralization identified more than 100 meters beyond the MRE boundary.”
Overview
The Project is located 110 kilometers east of Lebel-sur-Quévillon, which is 150 km to the city of Val d’Or, in the mining-friendly province of Quebec, within the Abitibi Greenstone Belt. Past production occurred in 2006-2008 at Barry where over 600,000 tonnes were processed at the Bachelor Mill, producing over 43,000 ounces of gold. In 2018, Bonterra constructed an underground exploration ramp extending to 100 m below the surface. The PEA assumes the availability of certain existing infrastructure and the ability to obtain or maintain the approvals, mining lease, essential permits and third-party arrangements required to implement the development scenario. No assurance is provided that those assumptions will be realized or that the development scenario will be approved or implemented.
Mine Plan and Production Overview
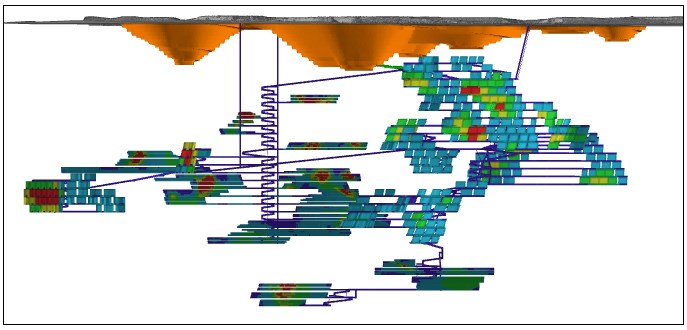
Bonterra’s PEA mine plan contemplates eight years of mine operations, during which approximately 700,000 ounces of gold are expected to be produced. It also contemplates mining using a combination of underground and open pit methods (see Figure 1), with the extracted mineralized material processed at a nearby toll-milling facility. The open pit and underground mine plans were evaluated using DeswikTM algorithms to create optimal mineable shapes based on economic and technical parameters such as mine dilution and recovery.
Open pit mine design consists of 10.0 m high benches with an overall slope angle of 45 degrees. Proposed production totals 4.9 Mt, along with 33.0 Mt of overburden and waste rock, leading to a LOM strip ratio of 6.7. The open pit operation has an average mined grade of 1.9 g/t Au, resulting in total contained gold production of more than 302,000 ounces. The PEA contemplates underground mining continuing throughout the open pit mining operations. The underground mine plan comprises 3.4 Mt of mineralized material mined at an average grade of 4.05 g/t Au, containing approximately 448,000 ounces of gold. The contemplated underground mining methods consist of a combination of long-hole mining and modified cut and fill operation. The metallurgical information presented in the PEA was based, among other sources, on historical production data from Barry open pit mineralized material processed at Bachelor Mill.
Figure 1: Longitudinal section showing PEA Open pit and Underground Stoping
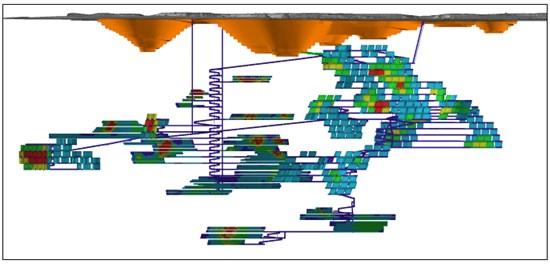
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/1528/318781_42004efbc48ca92a_001full.jpg
Base Case
The economic analysis was conducted using a 5% discount rate. On an after-tax basis, the Project generates a net present value at a 5% discount rate (“NPV₅%”) of C$665 million, an internal rate of return of 54%, and a payback period of 2.5 years. The life-of-mine cash cost and all-in sustaining cost are estimated at C$2,411/oz and C$3,017/oz, respectively. A summary of the project economics is listed below:
Base Case PEA Summary (100% Project Basis)
| Description | Unit | Value |
| Total Tonnes Mined (Open Pit and Underground) | Mt | 8.4 |
| Average Diluted Gold Grade | g/t | 2.79 |
| Total Gold Contained | oz | 749,944 |
| Overall Gold Recovery | % | 93.0 |
| Total Gold Payable | oz | 696,772 |
| Mine Life | years | 7.2 |
| Average Annual Gold Produced | Au oz per year | 87,097 |
| Long Term Gold Price | US$/oz | 3,500 |
| Exchange Rate | CAD: USD | 0.74 |
| Discount Rate | % | 5 |
| Total LOM Revenue | C$M | 3,292 |
| Total Royalty Costs (including buyback) | C$M | 66 |
| Total LOM Operating Costs | C$M | 1,682 |
| Total Initial Capital | C$M | 119 |
| Cash Cost per ounce | C$/oz | 2,411 |
| Total LOM Sustaining Costs | C$M | 354 |
| All-in-Sustaining Capital (AISC) | C$/oz | 3,017 |
| Total LOM Pre-tax Cash Flow | C$M | 1,183 |
| Average Annual Pre-tax Cash Flow | C$M | 131 |
| Total LOM After-tax Free Cash Flow | C$M | 827 |
| Average Annual After-tax Free Cash Flow | C$M | 92 |
| After-tax Summary | ||
| After-tax NPV5% | C$M | 665 |
| After-tax IRR | % | 53.5 |
| After-tax Payback | years | 2.5 |
Capital and Operating Costs
The initial capital cost for the Project is estimated at C$118.7 million, including a C$23.7 million contingency, equivalent 25% of the pre-contingency capital cost estimate. Infrastructure costs account for C$42.4 million of the initial capital cost, comprising C$41.8 million for power and electrical infrastructure and C$0.6 million for the processing plant. General and civil costs are estimated at C$33.4 million, while the remaining C$19.2 million comprises indirect costs. The initial capital estimate for processing is based on a toll-milling operating model.
The sustaining capital cost is estimated at C$354.3 million. Most of the underground sustaining capital is associated with lateral and vertical development (C$210.8 million) and the construction of an electrical station (C$36.6 million). The remaining underground capital expenditures are related to infrastructure and mine services, including dewatering, ventilation, and construction. Site closure cost is estimated at C$7.3 million.
The total capital cost for the project is estimated at C$480.3 million as summarized in the table below.
Barry Capital Cost Summary (100% Project Basis)
| Capital Cost Description | CAPEX C$M |
| General and Civil | 33.4 |
| Infrastructures | 42.4 |
| Indirect Costs | 19.2 |
| Contingency | 23.7 |
| Initial CAPEX | 118.7 |
| Sustaining Capex | 354.3 |
| Site Closure Costs | 7.3 |
| Total | 480.3 |
Project Operating Cost Summary (100% Project Basis)
| Operating Cost Description | Unit | Cost |
| Mining – Open pit | C$/t milled | 73.33 |
| Mining – Underground | C$/t milled | 199.28 |
| Processing | C$/t milled | 44.56 |
| Transport & Refining | C$/t milled | 10.41 |
| G&A | C$/t milled | 20.86 |
| Total | C$/t milled | 200.95 (1) |
Cash Cost and All in Sustaining Costs Summary (100% Project Basis)
| Cash and AISC Costs | Unit | Cost |
| Cash Cost | C$/oz | 2,411 |
| AISC | C$/oz | 3,017 |
| Cash Cost | US$/oz | 1,786 |
| AISC | US$/oz | 2,235 |
Sensitivity Analysis
A financial sensitivity analysis was conducted on the PEA, after-tax NPV and IRR of the Project, using the following variables: capital costs, CAD: USD exchange rate and the price of gold. The after-tax results for the Project IRR and NPV5% based on the sensitivity analysis are summarized below:
NPV Sensitivity Results (after-tax) for Gold Price and Exchange Rate Variations
(100% Project Basis)
| NPV@5% (C$ M) | |||||
| Gold Price | US$2,500 | US$3,000 | US$3,500 | US$4,000 | US$4,500 |
| Exchange Rate | |||||
| 1.43 | 190 | 493 | 774 | 1,046 | 1,313 |
| 1.41 | 163 | 469 | 747 | 1,016 | 1,279 |
| 1.39 | 133 | 445 | 720 | 985 | 1,246 |
| 1.37 | 102 | 421 | 692 | 955 | 1,212 |
| 1.35 | 71 | 397 | 665 | 925 | 1,179 |
| 1.33 | 39 | 373 | 638 | 895 | 1,145 |
| 1.31 | 8 | 348 | 610 | 864 | 1,112 |
| 1.29 | (23) | 324 | 583 | 833 | 1,078 |
| 1.27 | (54) | 299 | 555 | 802 | 1,044 |
NPV Sensitivity Results (after-tax) for Capital and Operating Costs Variations
(100% Project Basis)
| NPV@5% (C$ M) | |||||||||
| CAPEX | 60% | 70% | 80% | 90% | 100% | 110% | 120% | 130% | 140% |
| OPEX | |||||||||
| 60% | 1,340 | 1,332 | 1,323 | 1,315 | 1,306 | 1,297 | 1,289 | 1,280 | 1,271 |
| 70% | 1,180 | 1,171 | 1,163 | 1,154 | 1,146 | 1,137 | 1,128 | 1,120 | 1,111 |
| 80% | 1,020 | 1,011 | 1,003 | 994 | 986 | 977 | 968 | 960 | 951 |
| 90% | 860 | 851 | 843 | 834 | 826 | 817 | 808 | 799 | 791 |
| 100% | 699 | 691 | 682 | 674 | 665 | 657 | 648 | 639 | 631 |
| 110% | 539 | 531 | 522 | 514 | 505 | 497 | 488 | 479 | 470 |
| 120% | 379 | 371 | 362 | 354 | 345 | 336 | 328 | 319 | 310 |
| 130% | 219 | 210 | 202 | 193 | 185 | 176 | 167 | 159 | 150 |
| 140% | 59 | 50 | 42 | 33 | 25 | 16 | 7 | (1) | (10) |
The sensitivity analysis reveals that the price of gold has the most significant influence on both NPV and IRR. After the price of gold, the NPV and IRR were most impacted by the OPEX and to a lesser extent by variation in capital costs and exchange rate.
Mineral Resources
The Company notes that mineral resources are not mineral reserves as they do not have demonstrated economic viability. The Company further notes that a PEA is preliminary in nature and may include inferred mineral resources that are considered too speculative geologically to have economic consideration applied to them that would enable them to be categorized as mineral reserves, and there is no certainty that the PEA will be realized. All figures are stated in Canadian dollars unless otherwise stated.
Phoenix JV
Under the JV Agreement, Gold Fields has the right to acquire a 70% interest in the Project by spending C$30 million in work expenditures, with a minimum spending commitment of C$10 million per year over a three-year period (see press release dated November 28, 2023).
This news release, including the PEA disclosed herein, has been prepared solely by the Company and is based on information available to the Company as of the date hereof. Neither Gold Fields nor its affiliate Windfall Mining participated in the preparation of, or has verified, approved, or endorsed the PEA or the content of this news release, and no representation or warranty is made by Gold Fields or Windfall Mining with respect thereto. References to the Phoenix Joint Venture are provided for contextual purposes only and should not be construed as statements made by, or on behalf of, Gold Fields or Windfall Mining.
Bonterra’s PEA does not constitute an approved program, budget or development decision under the JV Agreement. Nothing in this news release should be interpreted as indicating that Gold Fields or Windfall Mining intends to pursue, fund or implement the mine plan or development scenario described in the PEA. If Gold Fields completes the earn-in, future exploration, evaluation and development activities will be determined in accordance with the applicable governance, operatorship and approval provisions of the JV Agreement.
QUALIFIED PERSONS
The PEA production scenario is based on the Measured, Indicated and Inferred mineral resources from the 2026 MRE issued on February 23, 2026. The PEA was prepared by the following Qualified Persons as defined by NI 43-101: Gabriel Monty, P.Eng.; Vera Gella, P.Eng.; Benoit Ouellet, P.Eng. Hugo Latulippe, P.Eng, of BBA Consultants; and Antoine Yassa, P.Geo. OGQ of P&E Mining Consultants Inc. as it relates to MREs, all each of whom are independent of the Company in accordance with NI 43-101. They are not aware of any environmental, permitting, legal, title, taxation, socio-economic, marketing, political, or other relevant factors that could materially affect the results of the PEA. The Qualified Persons have reviewed, verified, and approved the scientific and technical data for which they have responsibility contained in this news release pertaining to the PEA.
The full technical report, which is being prepared in accordance with NI 43-101 – Standards of Disclosure for Mineral Projects will be available on SEDAR+ (www.sedarplus.com) under the Company’s issuer profile within 45 days from this news release. The effective date of the PEA is October 8, 2026.
About Bonterra Resources Inc.
Bonterra is a Canadian gold exploration company with a portfolio of advanced exploration assets anchored by a central milling facility in Quebec, Canada. The Company’s assets include the Gladiator, Barry(1), Moroy, and Bachelor(2) gold deposits, which collectively hold 16.8 million tonnes at an average grade of 3.02 g/t Au for 1.63 million ounces of Measured & Indicated Mineral Resources, plus 15.6 Mt at 4.32 g/t Au for 2.17 Moz of Inferred Mineral Resources.
In November 2023, the Company entered into an earn-in and joint venture agreement with Osisko Mining Inc. for the Urban-Barry properties, which include the Gladiator and Barry deposits. In October 2024, Gold Fields Ltd, through a wholly owned Canadian subsidiary Windfall Mining Group Inc., completed the acquisition of Osisko Mining for C$2.16 billion. Windfall Mining Group Inc. is now the counterparty to the JV Agreement and can continue to earn a 70% interest in the joint venture by incurring C$30 million in work expenditures on or before November 2026 (including expenditures incurred by Osisko Mining prior to October 2024). This strategic transaction highlights Bonterra’s dedication to advancing its exploration assets, marking a significant step towards development.
1) See news release of the Company dated February 23, 2026, and titled “Bonterra Reports Significant Mineral Resources Growth at Barry and Gladiator Deposits” for further details.
2) See news release of the Company dated April 1, 2026, and titled “Bonterra Reports Significant Mineral Resource Growth at Bachelor and Moroy, 100% owned Deposits and Provides Corporate Updates” for further details.
FOR ADDITIONAL INFORMATION
Cesar Gonzalez, Executive Chairman & Interim CEO
ir@btrgold.com
2872 Sullivan Road, Suite 2, Val d’Or, Quebec J9P 0B9
819-825-8678 | Website: www.btrgold.com
Brutus Mining Inc. (CSE: BRU) (FSE: ZI3) is pleased to announce that it has closed its non-brokered ... READ MORE
Jaguar Uranium Corp. (NYSE American: JAGU) is pleased to announce an independent Mineral Resource E... READ MORE
Auro Metals Inc. (TSX-V: AURO) (OTCQB: AURFF), is pleased to announce the assay results of the fina... READ MORE
Endeavour Silver Corp. (NYSE: EXK) (TSX: EDR) is pleased to announce that repairs to the primary bal... READ MORE
Scorpio Gold Corp. (NASDAQ: SGLD) (TSX-V: SGLD) (OTCQB: SRCRF) (FSE: RY9) is pleased to announce re... READ MORE